Assets

iPulse AI Editorial Picks research

Best AI Stocks To Buy

Explore the best artificial intelligence stocks to buy according to iPulse AI's independent agentic investment research. The analysis combines one-year return potential with five-year trend confirmation, multi-agent consensus, business quality, financial health, valuation and risk resilience. Every selection includes a clear investment thesis, projected returns, catalysts and the risks that could change the outlook, helping investors compare high-conviction ideas using evidence rather than a single score or short-term price move.

Explore overall iPulse AI portfolio strategies and performance

Editorial ApproverRusslan Ramdowar iPulse AI Engine V6 15 min read
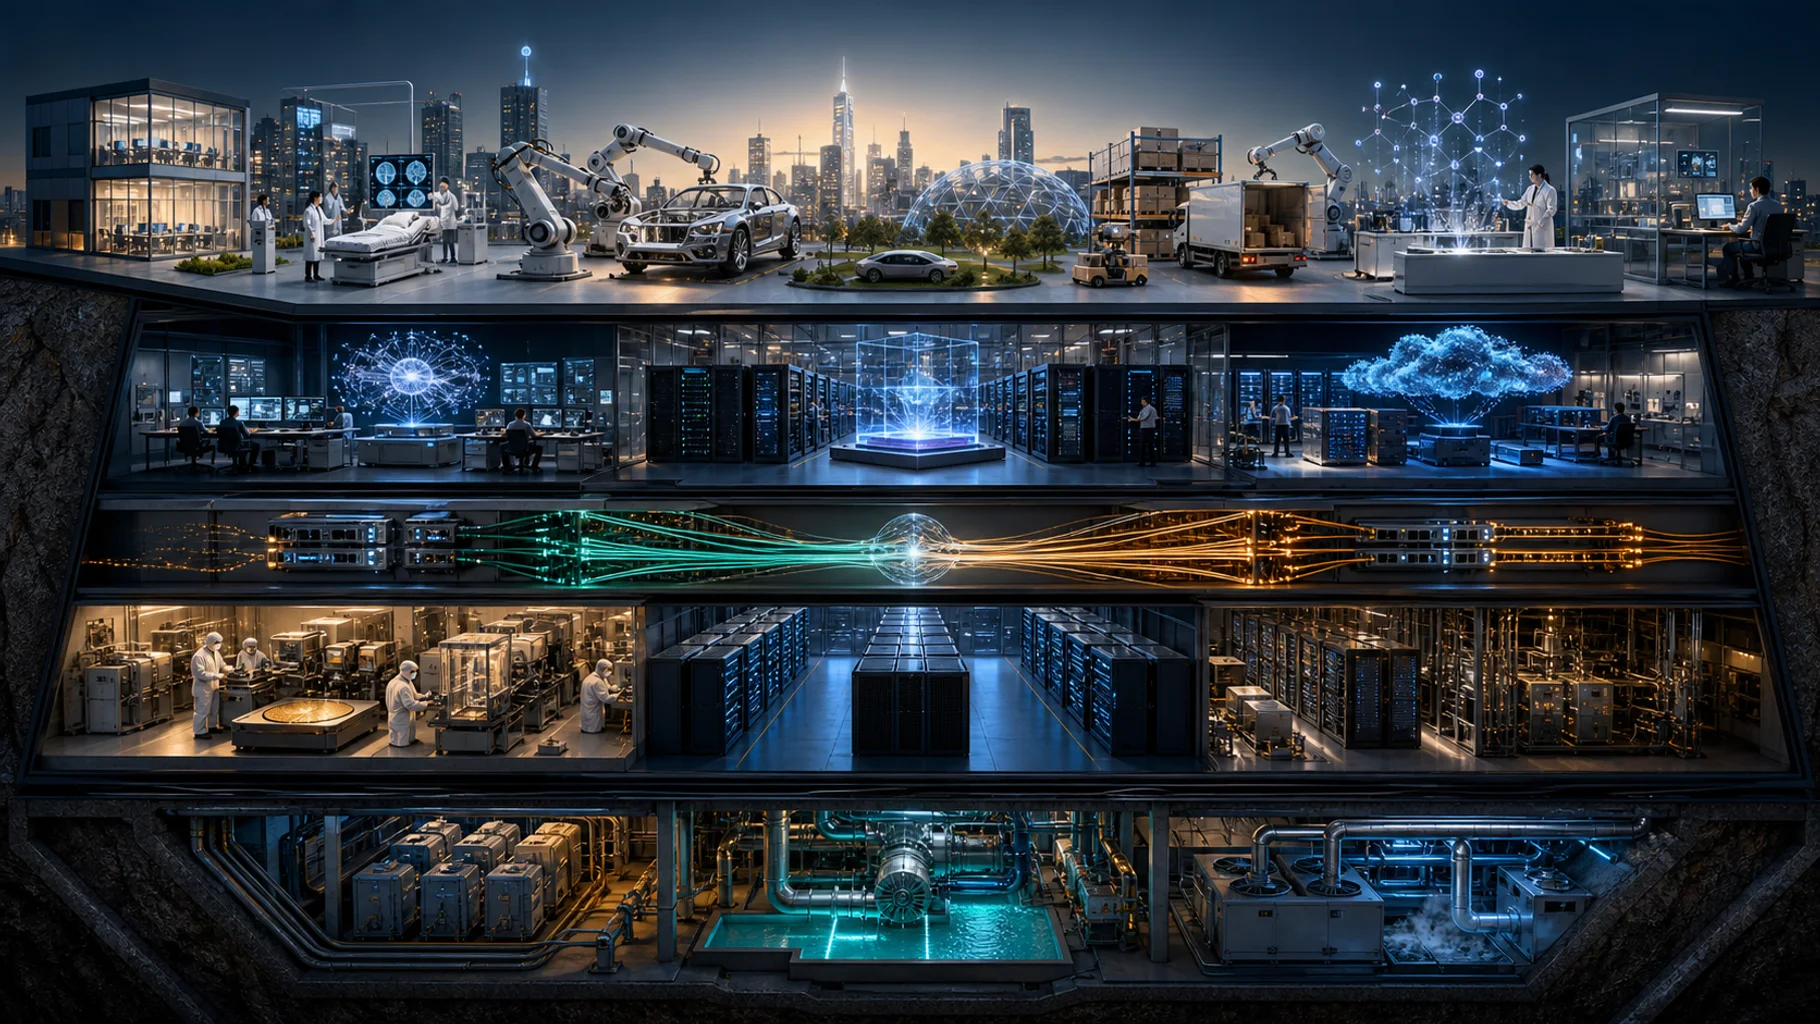
An architectural cutaway connects semiconductor fabrication, power, networking, data centers, model laboratories, robotics, and applied artificial intelligence.

Our Approach: The broad screening universe covers about 100,000 stocks; it is not the number of assets with published forecasts. For this edition, 376 assets passed preselection and underwent deep multi-agent analysis. iPulse AI Engine V6 ranked the top 7, and 7 Editorial Top Picks passed the separate evidence review and approval workflow. Read the detailed methodology

Editorial Picks countdown

Top 7 Editorial Picks

ASM:AMSHQ:Listed:

Information Technology ยท Semiconductor Materials & Equipment

Semiconductor equipment company focused on deposition technologies used in advanced logic, memory, and high-performance packaging flows.

RatingBuy

Latest editorial review

Reviewed through 24 Aug 2026

Based on deep-analysis report: 5 Jul 2026 ยท newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

The editor's view

The original investment case and current rating remain supported as of 2026-08-24T15:12:25Z. The quarterly results refreshed semiconductor-equipment demand, backlog, and margin evidence without a thesis-breaking event. Monitor the next material filing, policy decision, protocol release, or operating update.

What to watch

A physical blockade or kinetic military escalation in the Taiwan Strait would instantly freeze construction and tooling of advanced fabrication facilities. The next material filing, operating update, policy decision, or protocol release for a change in the load-bearing thesis.

+86.2%
Excl. dividends: +81.6%
0.5%Dividend yield (net)
โ€”Buyback yield
38.0x
73/100
32/100

Flagship insight

Why Atomic Precision Moats Will Outlast the Impending AI Infrastructure Valuation Reset

High consensus exists regarding the asset's structural atomic layer deposition monopoly, which decouples long-term earnings from raw wafer volumes. However, sharp divergence persists over near-term valuation multiples. While sovereign fab duplication provides a policy-driven demand floor, tightening export controls and macroeconomic rate gravity present immediate friction.

The company is a vital player in the microchip industry because it owns a near-monopoly on the specialized technology needed to build the world's most advanced computer chips. As chips shrink to microscopic sizes, manufacturers must use atomic-level precision, making this company's tools absolutely necessary. Even if the overall chip market slows down, the demand for these specific advanced tools is expected to rise. Additionally, governments in the US and Europe are spending billions to build local chip factories, which guarantees a steady stream of orders. However, the stock is currently very expensive, meaning its price could experience a bumpy ride if the broader market cools down or if new trade restrictions with China take effect.

  • The shift to advanced chip designs requires more precise tools, boosting demand regardless of overall market growth.
  • Government subsidies are funding new, local chip factories, creating a reliable pipeline of equipment orders.
  • A debt-free balance sheet and massive cash reserves protect the company from rising interest rates.
  • Strict trade restrictions could suddenly cut off a large portion of the company's sales to China.
  • The stock's high price tag leaves no room for error, making it vulnerable to sudden market drops.
  • Any pause in big tech spending on artificial intelligence could temporarily delay new equipment orders.

Advisor consensus

Overall, advisors show very high price-direction agreement and low disagreement. Read on to see where advisor views still differ.

The primary disagreement across the reports centers on the severity and timing of valuation multiple compression versus fundamental earnings growth. One school of thought argues that the asset's absolute technological monopoly and sovereign-backed demand floor will easily overwhelm any multiple contraction, justifying the current premium. Conversely, more cautious perspectives warn that buying a cyclical equipment supplier at peak margins and peak multiples guarantees poor medium-term returns, anticipating a severe AI capex digestion phase that will violently compress the P/E multiple toward historical mid-cycle norms.

Risk and opportunity map

Longer-term opportunities

Accelerated Backside Power Delivery Adoption

Innovation And Product

35% probabilityStock price impact: +20.0%Earnings impact: Not quantified

If major logic foundries accelerate the deployment of Backside Power Delivery Networks ahead of schedule to resolve critical AI thermal constraints, ALD tool intensity will undergo a vertical step-function increase. This architectural shift mandates novel conformal dielectric layers on the wafer's reverse face, structurally widening the addressable market overnight.

Competitor Technology Failure or Intel Resurgence

Competitive Positioning

25% probabilityStock price impact: +15.0%Earnings impact: Not quantified

If generalized equipment competitors fail to certify their deposition alternatives for the critical 1.4nm logic transition, or if a subsidized Intel foundry successfully executes its advanced node roadmap, a fierce competitive tooling race will emerge. This would trigger panic-buying of essential ALD platforms, driving parabolic, unmodeled backlog growth.

Tail risks

Taiwan Strait Kinetic Conflict or Blockade

Political And Geopolitical

20% probabilityStock price impact: -45.0%Earnings impact: Not quantified

A physical blockade or kinetic military escalation in the Taiwan Strait would instantly freeze construction and tooling of advanced fabrication facilities. Given the extreme concentration of leading-edge demand in Taiwan, this event would sever critical cash flows, voiding backlogs and triggering a catastrophic, permanent impairment of capital.

Blanket China Servicing and Legacy Embargo

Regulatory

35% probabilityStock price impact: -30.0%Earnings impact: Not quantified

If geopolitical tensions prompt Western regulators to enact a blanket ban on both new equipment sales and the servicing or maintenance of the existing installed base in China, the resulting revenue shock would instantly evaporate roughly 30% of the asset's earnings power, forcing a violent valuation downgrade.
0700:HKEXHQ:Listed:

Communication Services ยท Interactive Media & Services

Chinese multinational technology conglomerate specializing in internet services, mobile games, social networks, and digital payments including WeChat.

RatingBuy

Latest editorial review

Reviewed through 24 Aug 2026

Based on deep-analysis report: 5 Jul 2026 ยท newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

The editor's view

The original investment case and current rating remain supported as of 2026-08-24T15:12:25Z. The interim update refreshed gaming, advertising, cloud, AI spending, and cash evidence without invalidating the original investment case. Monitor the next material filing, policy decision, protocol release, or operating update.

What to watch

A direct military conflict or severe blockade scenario involving Taiwan would trigger catastrophic Western sanctions and asset freezes. The next material filing, operating update, policy decision, or protocol release for a change in the load-bearing thesis.

+87.0%
Excl. dividends: +79.6%
0.8%Dividend yield (net)
โ€”Buyback yield
15.2x
65/100
68/100

Flagship insight

How Algorithmic Efficiency and Capital Returns Shield This Hidden Tech Giant

There is high consensus across reports that this digital platform represents a resilient value compounder. Primary drivers include aggressive capital returns and sovereign AI integration, which offset frictions from domestic macroeconomic stagnation and geopolitical decoupling. The asset offers robust downside protection through its fortress balance sheet and unassailable network effects.

This digital giant is changing from a fast-growing tech company into a highly efficient cash machine. Even though the general public is worried about the weak local economy and political tensions, the company's core business of social media, gaming, and payments remains incredibly strong. Instead of wasting money on expensive global AI battles, the company is putting smart AI tools directly into its popular apps, which helps it make more money from advertising. Most importantly, the company is using its massive cash reserves to buy back its own cheap stock, which automatically makes each remaining share more valuable for everyday investors.

  • Massive stock buybacks act as a safety net, steadily increasing the value of your investment.
  • The company's popular apps are essential for daily life, making it almost impossible for competitors to steal users.
  • New AI features are making advertising more profitable, helping to boost overall earnings.
  • Heavy spending on new technology might temporarily lower official profits over the next year.
  • Political tensions with Western countries could keep the stock price lower than it deserves to be.
  • The company has almost no debt, meaning it can easily survive global economic downturns.

Advisor consensus

Overall, advisors show very high price-direction agreement and low disagreement. Read on to see where advisor views still differ.

The primary disagreement across reports centers on the expected volatility and the near-term margin impact of the AI capex surge. Some analyses assume that doubling AI spending to over 36 billion RMB will severely compress operating margins and threaten the share buyback program, viewing the investment as a defensive necessity. Conversely, other reports argue that the capex is fully funded by off-balance-sheet portfolio liquidations, leaving core free cash flows untouched. There is also divergence regarding whether a forced US divestiture of gaming assets represents a catastrophic loss of international growth or an elite capital allocation catalyst to unlock hidden value.

Risk and opportunity map

Longer-term opportunities

CFIUS Forced Divestiture Windfall

Capital Allocation

35% probabilityStock price impact: +25.0%Earnings impact: Not quantified

If Western regulators force the company to divest its highly valuable international gaming stakes on national security grounds, it could trigger a massive value-unlock. Liquidating these mature assets at premium Western valuations would repatriate billions of dollars in cash. Management would likely distribute this windfall via special dividends or an unprecedented acceleration of its share buyback program, collapsing the conglomerate discount and driving a rapid upward repricing of the stock.

Agentic WeChat Commerce Breakout

Innovation And Product

30% probabilityStock price impact: +22.0%Earnings impact: Not quantified

The successful integration of autonomous AI agents natively into the WeChat ecosystem could transform the platform into a frictionless transactional operating system. If users shift from manual searches to delegating complex e-commerce, travel, and productivity tasks to AI agents, the company would capture massive new subscription and transaction fees. This breakout would instantly validate its heavy AI investments, structurally elevating terminal operating margins and forcing a violent upward multiple re-rating.

Tail risks

Kinetic Cross-Strait Conflict

Political And Geopolitical

15% probabilityStock price impact: -60.0%Earnings impact: Not quantified

A direct military conflict or severe blockade scenario involving Taiwan would trigger catastrophic Western sanctions and asset freezes. Under this tail risk, the company would face forced delisting from global indices, and offshore capital would be completely evicted. While the domestic business operations would survive, the equity value for global investors would be structurally and permanently impaired, resulting in an immediate and devastating collapse in the stock price.

Renewed Punitive Domestic Regulation

Regulatory

20% probabilityStock price impact: -35.0%Earnings impact: Not quantified

If Beijing abruptly abandons its current supportive stance toward technology champions and implements draconian anti-monopoly mandates or punitive tax hikes, the company's economic moat would be severely damaged. A forced structural breakup of WeChat's payment architecture or strict adult gaming bans would permanently impair its cash-generating capacity, signaling that the state views the enterprise strictly as a taxable utility and destroying the institutional investment thesis.

The leading five

The Top 5

#5 โ†’ #1

Five ideas remain. Each passed the full editorial review and earned a place in this edition's highest-conviction group.

005930:KRXHQ:Listed:

Information Technology ยท Technology Hardware, Storage & Peripherals

South Korean multinational electronics company and global manufacturer of smartphones, semiconductors, and consumer electronics.

RatingBuy

Latest editorial review

Reviewed through 24 Aug 2026

Based on deep-analysis report: 5 Jul 2026 ยท newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

The editor's view

The original investment case and current rating remain supported as of 2026-08-24T15:12:25Z. The results refreshed memory, foundry, device, and AI-demand evidence without a thesis-breaking event. Monitor the next material filing, policy decision, protocol release, or operating update.

What to watch

Enterprise adoption of generative artificial intelligence stalls due to persistent technical limitations or security concerns, prompting hyperscalers to slash infrastructure budgets by over fifty percent. The next material filing, operating update, policy decision, or protocol release for a change in the load-bearing thesis.

+102.0%
Excl. dividends: +87.3%
1.5%Dividend yield (net)
โ€”Buyback yield
20.8x
64/100
65/100

Flagship insight

How Geopolitical Redundancy and Memory Integration Are Reshaping Advanced Silicon Moats

A sharp divergence exists between short-term cyclical memory bears and long-term structural infrastructure bulls. High consensus supports the asset's unmatched vertical integration of logic, high-bandwidth memory, and advanced packaging as a critical geopolitical hedge, though massive capital expenditure requirements and potential hyperscaler demand digestion present near-term margin friction.

The big picture is that the company is shifting from making everyday consumer gadgets to providing the essential physical backbone for the global artificial intelligence boom. While the semiconductor industry is known for its ups and downs, the massive demand for advanced memory chips creates a strong long-term growth path. The company's debt-free balance sheet acts as a financial shield, allowing it to spend heavily on new technology even when global interest rates are high. This massive spending makes it incredibly difficult for smaller competitors to catch up.

  • The company is the only player globally that can design chips, manufacture advanced memory, and package them together.
  • Global tech giants are eager to find alternatives to Taiwanese chipmakers to protect their supply chains from political risks.
  • Heavy spending on advanced factories creates a massive barrier to entry, keeping competitors at a distance.
  • If tech companies slow down their artificial intelligence spending, the market could face a temporary oversupply of chips.
  • Struggles to improve manufacturing efficiency on the newest, smallest chips could limit near-term profit growth.
  • Everyday consumer electronics like smartphones and home appliances face slower growth due to inflation squeezing household budgets.

Advisor consensus

Overall, advisors show high price-direction agreement with limited disagreement. Read on to see where advisor views still differ.

The primary disagreement across the reports centers on the duration and structural nature of the current memory cycle. One faction argues that artificial intelligence demand has fundamentally altered the industry's capital cycle, establishing a permanent, high-margin infrastructure baseline. Conversely, another faction maintains that the massive capital expenditure response will inevitably lead to a severe supply glut and margin collapse by late 2027, adhering to classic commodity cycle dynamics. There is also minor disagreement regarding the timeline for advanced foundry yield stabilization and the drag of legacy consumer divisions.

Risk and opportunity map

Longer-term opportunities

Primary Hyperscaler Turnkey Contract Win

Competitive Positioning

35% probabilityStock price impact: +25.0%Earnings impact: Not quantified

A major Western cloud provider formally designates the asset as the primary manufacturer for its next-generation custom artificial intelligence accelerators, utilizing the combined logic, memory, and packaging bundle. This would shatter the incumbent's monopoly narrative, immediately closing the valuation multiple gap and unlocking billions in high-margin structural revenue.

Taiwan Strait Supply Disruption

Political And Geopolitical

15% probabilityStock price impact: +45.0%Earnings impact: Not quantified

A severe kinetic escalation or maritime blockade in the Taiwan Strait abruptly halts advanced logic shipments from the dominant incumbent. Western tech giants would be forced to immediately migrate all advanced silicon volume to the asset's foundry. This black-swan event would instantly transform the asset into a civilizational monopoly, triggering unprecedented multiple expansion.

Tail risks

Artificial Intelligence Capital Expenditure Collapse

Macroeconomic And Macrofinancial

30% probabilityStock price impact: -35.0%Earnings impact: Not quantified

Enterprise adoption of generative artificial intelligence stalls due to persistent technical limitations or security concerns, prompting hyperscalers to slash infrastructure budgets by over fifty percent. This sudden demand collapse would strand the asset's massive capital investments, triggering severe inventory write-downs and deep operating losses in the semiconductor division.

Advanced Node Yield Failure

Operational Efficiency

25% probabilityStock price impact: -25.0%Earnings impact: Not quantified

The asset structurally fails to achieve commercially viable yields on its next-generation sub-2nm Gate-All-Around nodes, leading to severe thermal leakage or performance issues. Hyperscalers would abandon their diversification mandates and retreat entirely to the dominant incumbent, rendering the asset's multi-billion-dollar advanced fabrication plants stranded assets.

META:NASDAQHQ:Listed:

Communication Services ยท Interactive Media & Services

Social media and virtual reality company connecting billions globally through Facebook, Instagram, WhatsApp, and metaverse technologies. Formerly known as Facebook.

RatingBuy

Latest editorial review

Reviewed through 24 Aug 2026

Based on deep-analysis report: 5 Jul 2026 ยท newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

The editor's view

The original investment case and current rating remain supported as of 2026-08-24T15:12:25Z. The results refreshed advertising, AI investment, and capital-intensity evidence. Spending risk remains material but does not make the thesis stale. Monitor the next material filing, policy decision, protocol release, or operating update.

What to watch

A sudden breakthrough in algorithmic efficiency that allows competitors to train and run frontier models on a fraction of the compute. The next material filing, operating update, policy decision, or protocol release for a change in the load-bearing thesis.

+105.0%
Excl. dividends: +103.0%
0.2%Dividend yield (net)
โ€”Buyback yield
20.7x
75/100
51/100

Flagship insight

Why Massive Infrastructure Spending Is Secretly Creating An Unassailable AI Monopoly

A high consensus across reports reveals that massive infrastructure capital expenditures are establishing a dominant compute utility. While near-term depreciation pressures margins, the strategic deployment of custom silicon and open-source models commoditizes rivals, securing long-term pricing power and transactional dominance in global digital commerce.

The company is changing from a social media business into a massive artificial intelligence powerhouse. Many average investors are worried about the huge amount of money being spent on computer chips and data centers. However, this heavy spending is actually building a giant wall around the business that competitors cannot climb. By giving away its AI software for free, the company is making it impossible for rivals to charge for theirs, while keeping users locked into its own apps.

  • Huge spending on computer hardware creates a massive physical advantage that smaller rivals simply cannot afford.
  • Giving away AI software for free destroys the business models of competitors while keeping developers in its ecosystem.
  • Custom-designed microchips will lower the long-term costs of running advanced AI features across all apps.
  • Smart glasses and wearable devices offer a new way to connect with users, bypassing Apple and Google stores.
  • High interest rates hurt smaller tech companies, but this cash-rich giant can fund its own growth easily.
  • Heavy accounting charges from new hardware will temporarily lower reported profits, which might scare short-term investors.

Advisor consensus

Overall, advisors show very high price-direction agreement and low disagreement. Read on to see where advisor views still differ.

The primary disagreement across the reports centers on the monetization timeline and capital efficiency of the massive AI infrastructure spend. Bullish perspectives argue that the capital expenditures are already yielding immediate, high-velocity returns through core ad-targeting improvements and automated ad systems, justifying the investment. Conversely, bearish viewpoints emphasize the severe depreciation lag that will inevitably compress GAAP operating margins over the next 18 to 24 months, warning of a potential stranded-asset scenario if agentic AI software development continues to face internal delays.

Risk and opportunity map

Longer-term opportunities

Commercial Compute-as-a-Service Launch

Innovation And Product

35% probabilityStock price impact: +40.0%Earnings impact: Not quantified

The formal commercialization of the company's excess GPU capacity into a dedicated enterprise cloud service. By leasing idle compute to external developers, the company would transition from a pure digital advertising platform to a major global cloud hyperscaler. This would instantly convert a widely feared capital expenditure liability into a high-margin, recurring revenue engine, triggering massive multiple expansion.

Wearables Hardware Platform Hegemony

Innovation And Product

30% probabilityStock price impact: +35.0%Earnings impact: Not quantified

The mainstream consumer adoption of augmented reality smart glasses as the primary post-smartphone computing interface. If the company successfully establishes its hardware and operating system as the dominant spatial computing standard, it would entirely bypass the Apple and Google mobile duopoly. This would eliminate app store taxes, secure absolute platform-level pricing power, and permanently protect its global distribution channels.

Tail risks

Algorithmic Efficiency Shock and Stranded Assets

Sector And Industry

25% probabilityStock price impact: -40.0%Earnings impact: Not quantified

A sudden breakthrough in algorithmic efficiency that allows competitors to train and run frontier models on a fraction of the compute. This would render the company's massive, brute-force GPU clusters obsolete overnight. The forced write-down of these multi-billion-dollar hardware assets would reduce years of accumulated shareholder value, branding the historic infrastructure pivot as a severe capital misallocation.

Regulatory Dismemberment and Forced Divestiture

Regulatory

20% probabilityStock price impact: -35.0%Earnings impact: Not quantified

An aggressive antitrust ruling by global regulators forcing the structural breakup of the company, such as the mandatory divestiture of Instagram or WhatsApp. This would instantly disrupt the core network effects and cross-platform data arbitrage that drive the company's pricing power. Stripped of its unified targeting apparatus, the resulting entities would face severe valuation discounts and increased competitive vulnerability.

The finalists

The Top 3

#3 โ†’ #1

The shortlist is over. These three stocks earned the strongest conviction in this edition. Count down to the research team's number-one pick.

Checking your access...

The winner

The Number-One Pick

The edition's highest-conviction selection, combining near-term opportunity with long-term confirmation.

Market context and selection approach

AI demand is spreading across semiconductors, platforms, cloud services, power, memory, and chip equipment, but capital intensity and weak returns on spending remain key risks.

Only assets carrying the governed AI category tag qualify. The review tests monetization, competition, supply, power, regulation, valuation, and customer concentration.

References

Frozen links are separated into editorial-review evidence, 5โ€“6 global-context references, and 3โ€“4 governed Researcher citations per selected asset. Duplicate URLs appear once; the combined citation list is capped at 30.

A. Editorial-review sources

  1. 1.Qualcomm Earnings Release Available on Investor Relations Website QUALCOMM Incorporated ยท ISSUER RELEASE ยท 29 Jul 2026, 00:00 UTChttps://investor.qualcomm.com/news-events/press-releases/news-details/2026/Qualcomm-Earnings-Release-Available-on-Companys-Investor-Relations-Website-67f54b885/default.aspxReviewed for: QUALCOMM Incorporated (QCOM.NASDAQ)
  2. 2.Vistra Reports Second Quarter 2026 Results Vistra Corp. ยท ISSUER RELEASE ยท 7 Aug 2026, 00:00 UTChttps://investor.vistracorp.com/2026-08-07-Vistra-Reports-Second-Quarter-2026-ResultsReviewed for: Vistra Energy Corp (VST.NYSE)
  3. 3.Baidu Announces Second Quarter 2026 Results Baidu, Inc. ยท ISSUER RELEASE ยท 18 Aug 2026, 00:00 UTChttps://ir.baidu.com/news-releases/news-release-details/baidu-announces-second-quarter-2026-resultsReviewed for: Baidu Inc ADR (BIDU.NASDAQ)

B. Global market context

These dated files capture broader market, macroeconomic, policy, and cross-asset context. Each frozen file is supplied as input to every advisor model during deep analysis; its citations never count toward an asset-specific minimum.

  1. 4.Federal Reservehttps://www.federalreserve.gov/monetarypolicy/fomccalendars.htm
  2. 5.US Bureau of Labor Statisticshttps://www.bls.gov/cpi/data.htm
  3. 6.US Bureau of Economic Analysishttps://www.bea.gov/data/gdp/gross-domestic-product
  4. 7.US Treasuryhttps://home.treasury.gov/resource-center/data-chart-center/interest-rates
  5. 8.US Energy Information Administrationhttps://www.eia.gov/
  6. 9.Reuters Worldhttps://www.reuters.com/world

C. Asset-specific deep-analysis sources

Captured by governed AI Researcher agents. Shared URLs are shown once and identify every selected asset they support.

Asset-specific Researcher citations remain available in each linked deep analysis above; this original edition did not add a second citation set.

Important information

Research scope and investor notice

Research scope

  • External evidence was limited to material current-event validation through the frozen cutoff; the underlying complete-batch analysis was not rerun.
  • Forecasts, ratings, ranks, returns, financial-health values, and risk values remain frozen and may not capture later events.
  • The named human editor reviewed the evidence and approved this edition for publication. Readers should inspect the cited sources and apply independent judgment.

Investor notice

AI-assisted editorial research for informational and educational purposes. This edition was reviewed and approved by a named human editor. It is not personalized investment advice or a promise of future performance.

Forecasts, ratings, and return estimates are uncertain and may change as new evidence becomes available.