Assets

iPulse AI Editorial Picks research

Best US Stocks

Explore the best US stocks according to iPulse AI's independent agentic investment research. The analysis combines one-year return potential with five-year trend confirmation, multi-agent consensus, business quality, financial health, valuation and risk resilience. Every selection includes a clear investment thesis, projected returns, catalysts and the risks that could change the outlook, helping investors compare high-conviction ideas using evidence rather than a single score or short-term price move.

Explore overall iPulse AI portfolio strategies and performance

Editorial ApproverRusslan Ramdowar iPulse AI Engine V7 15 min read
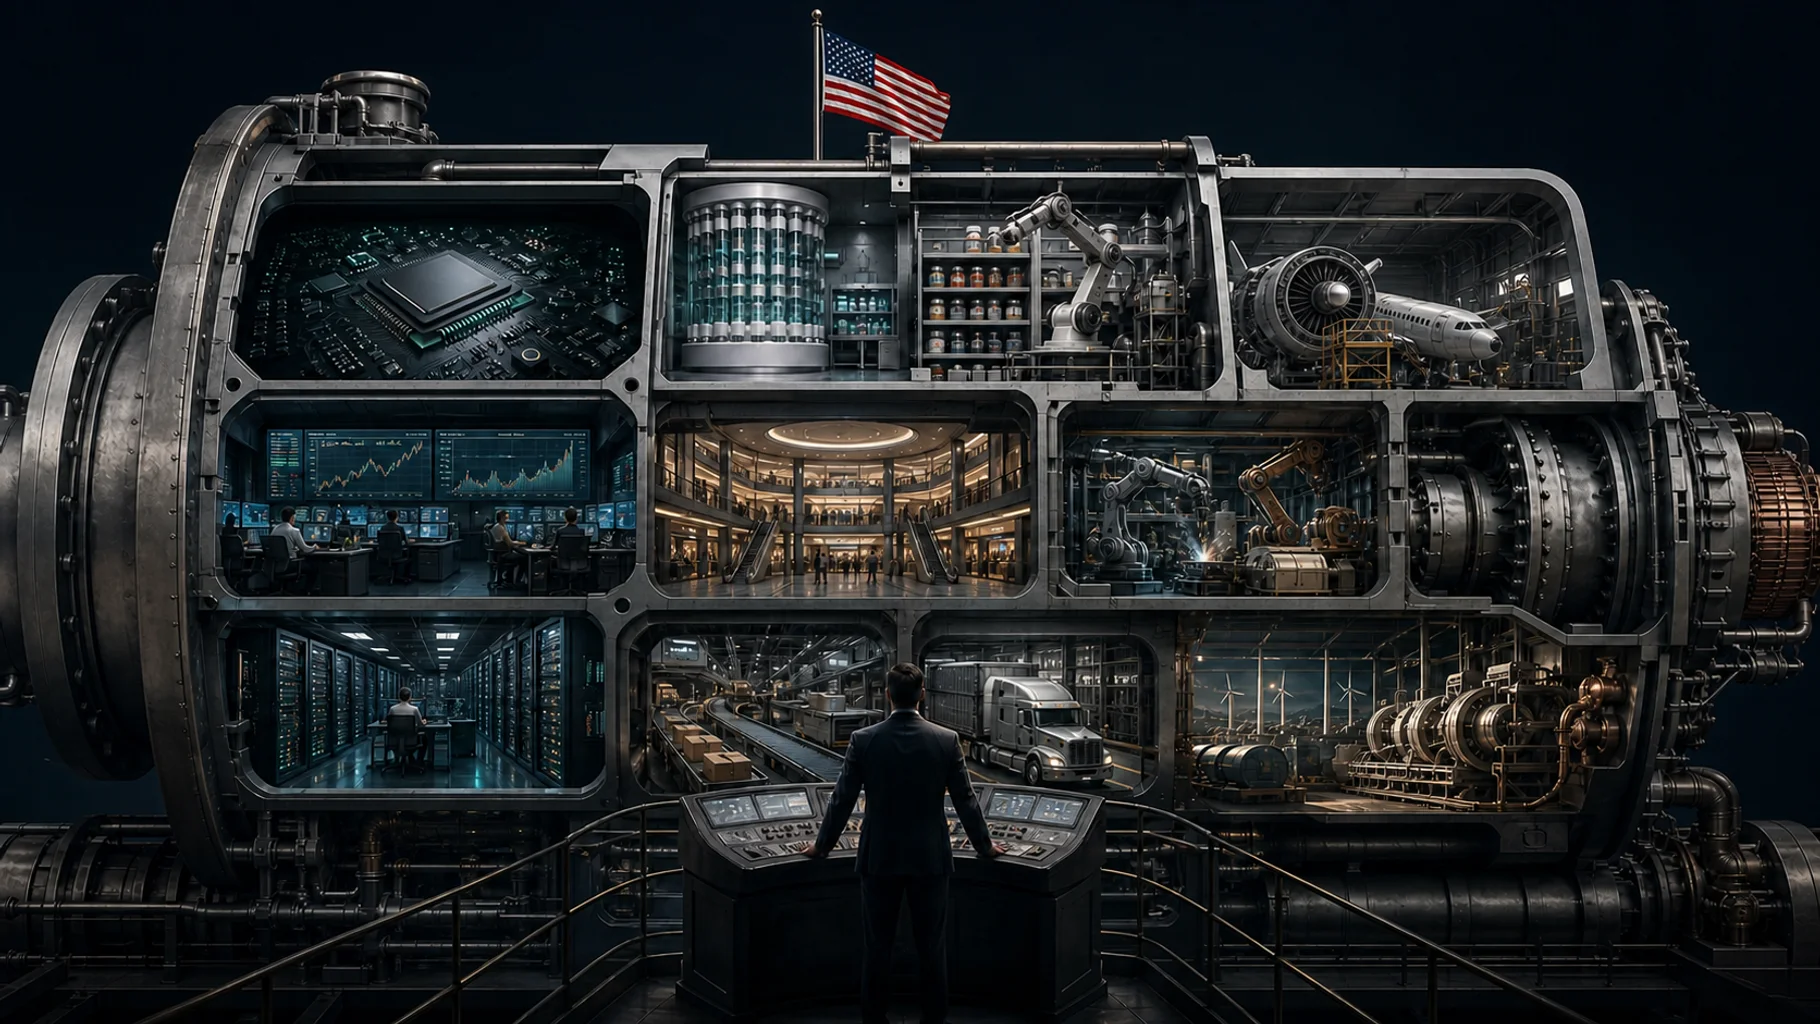
An analyst operates a cutaway American business engine containing semiconductor, healthcare, aerospace, finance, manufacturing, data, logistics, consumer, and energy chambers.

Our Approach: The broad screening universe covers about 100,000 stocks; it is not the number of assets with published forecasts. For this edition, 426 assets passed preselection and underwent deep multi-agent analysis. iPulse AI Engine V7 ranked the top 10, and 10 Editorial Top Picks passed the separate evidence review and approval workflow. Read the detailed methodology

Editorial Picks countdown

Top 10 Editorial Picks

BSX:NYSEHQ:Listed:

Health Care Β· Health Care Equipment

Medical technology company developing devices for cardiology, endoscopy, urology, neuromodulation, and other specialty procedures.

RatingStrong Buy

Latest editorial review

Reviewed through 5 Oct 2026

Based on deep-analysis report: 20 Sept 2026 Β· newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

a broad portfolio of minimally invasive treatments supports growth beyond any single medical product.

What to watch

Product setbacks or regulatory delays could interrupt adoption and raise the cost of commercial expansion.

+135.0%
Model rating: Strong Buy
β€”Dividend yield (net)
β€”Buyback yield
17.3x
Price as of: 2026-10-02
56/100
60/100

Flagship insight

Procedural Moats and Vascular Scale Drive Cash Recovery Beyond Disruption

Sharp divergence characterizes market sentiment between short-term electrophysiology share losses post-cyberattack and enduring procedural cash flows. High consensus affirms that non-discretionary cardiovascular demand and the Penumbra integration support cash-flow recovery, while competitive catheter pricing and elevated acquisition leverage remain primary structural frictions.

Recent stock declines reflect panic over shipping delays and catheter competition rather than a broken business. The company still generates over $3.6 billion in annual free cash flow, backed by essential heart, endoscopy, and urology devices that doctors use daily. Adding Penumbra creates a vascular powerhouse, while operational cost cuts protect profits. Even with higher borrowing costs, reliable patient demand ensures steady multi-year financial recovery.

  • Non-elective heart and vascular procedures cannot be postponed, guaranteeing consistent hospital demand through economic ups and downs.
  • Acquiring Penumbra establishes market leadership in blood clot removal, reducing reliance on any single cardiac device line.
  • Consistent debt repayment using robust operational cash flow will steadily rebuild investor confidence and expand per-share profits.

Advisor consensus

Overall, advisors show very high price-direction agreement and low disagreement. Read on to see where advisor views still differ.

The decisive disagreement centers on the durability of electrophysiology growth and the valuation multiple applied to normalized cash flows. Bullish analyses argue that Farapulse retains an unassailable clinical moat and model swift multiple re-expansion to 24x earnings as next-generation catheters launch. Conversely, cautious perspectives demonstrate that rival pulsed-field ablation platforms are causing irreversible market-share dilution, while $11 billion in acquisition debt will constrain per-share earnings growth. Observing whether domestic electrophysiology sales stabilize above 6% organic growth across upcoming quarterly prints will determine whether the thesis becomes an earnings compounder or a valuation-capped recovery.

Risk and opportunity map

Longer-term opportunities

CHAMPION First-Line Indication Approval

Innovation And Product

32% probabilityStock price impact: +32.0%Earnings impact: Not quantified

Extended clinical trial readouts establishing Watchman FLX superiority over direct oral anticoagulants in broad non-valvular atrial fibrillation cohorts could trigger FDA first-line label expansion by 2028. Moving from secondary contraindication therapy to primary prevention would quadruple the addressable patient population, injecting over $1 billion in high-margin revenue.

Accelerated Thrombectomy Synergies Realization

Competitive Positioning

28% probabilityStock price impact: +24.0%Earnings impact: Not quantified

Consolidating Penumbra's computer-assisted vacuum thrombectomy platforms through established multinational distribution channels could outpace modeled cross-selling projections by 30%. Rapid procedural adoption across European and Asian surgical centers by 2028 would generate substantial unexpected operating income, accelerating corporate debt retirement and multiple rerating.

Tail risks

Catastrophic Electrophysiology Safety Recall

Regulatory

18% probabilityStock price impact: -32.0%Earnings impact: Not quantified

An unexpected post-market clinical safety signal or severe tissue complication involving pulsed-field ablation catheters could prompt urgent FDA warning letters or commercial holds by 2027. Halting catheter shipments would forfeit market leadership to waiting competitors, trigger material litigation liabilities, and eliminate hundreds of millions in operating profit.

Antitrust Injunction Against Penumbra

Regulatory

20% probabilityStock price impact: -20.0%Earnings impact: Not quantified

Antitrust litigation by the Federal Trade Commission or European regulators challenging the $14.5 billion Penumbra transaction on vascular monopoly grounds could block the acquisition in late 2026. Deal termination would trigger heavy breakup fees, forfeiting entry into mechanical thrombectomy and stranding capital allocation strategy.
APP:NASDAQHQ:Listed:

Information Technology Β· Application Software

AppLovin Corporation provides end-to-end artificial intelligence-powered advertising solutions for businesses in the United States and internationally. It operates through two segments, Advertising and Apps.

RatingStrong Buy

Latest editorial review

Reviewed through 5 Oct 2026

Based on deep-analysis report: 20 Sept 2026 Β· newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

scalable advertising software can translate better campaign outcomes into cash with limited physical capital needs.

What to watch

Privacy restrictions or weaker advertiser returns could reduce demand and pressure platform economics.

+152.0%
Model rating: Buy
β€”Dividend yield (net)
β€”Buyback yield
20.6x
Price as of: 2026-10-02
77/100
32/100

Flagship insight

Programmatic Software Engine Unlocks Massive Cash Compounding Amid Market Disconnect

The research reveals high consensus regarding elite cash generation, with free cash flow converting over sixty percent of revenue at an eighty-four percent adjusted EBITDA margin. Consensus identifies self-serve e-commerce expansion as the primary growth driver, counterbalanced by platform operating system dependency as the foremost terminal risk.

AppLovin transformed itself from a mobile video game maker into an ultra-profitable advertising software company. By selling off its gaming studios and focusing entirely on its smart ad-matching software, the business now converts sixty-five cents of every dollar of sales into pure free cash flow. Wall Street worried after a short-term growth slowdown, pricing the company cheaply compared to its actual profits. While big tech platform rules remain an ongoing risk, the company's flood of cash easily funds massive share buybacks that reward patient shareholders.

  • Massive annual cash generation allows management to buy back shares aggressively, boosting the earnings behind every remaining share.
  • Expanding its ad system into online retail shopping gives the company a much larger market beyond mobile gaming.
  • Higher advertising competition and computing costs will naturally slow profit growth, making steady execution essential for long-term gains.

Advisor consensus

Overall, advisors show very high price-direction agreement and low disagreement. Read on to see where advisor views still differ.

The decisive disagreement centers on the durability of AppLovin's 75% operating margin and the velocity of its e-commerce expansion. Optimists argue that AXON's contextual machine learning operates with near-zero marginal compute costs, making 25% revenue compounding and multiple re-rating inevitable. Conversely, skeptics emphasize auction-density dilution, rising merchant acquisition costs, and platform gatekeeper risk from Apple, modeling structural margin compression toward 55%. Resolving this debate requires tracking non-gaming merchant spend and sequential EBITDA margin stability through upcoming 2027 earnings reports.

Risk and opportunity map

Longer-term opportunities

Connected television programmatic mediation breakthrough

Innovation And Product

32% probabilityStock price impact: +45.0%Earnings impact: Not quantified

Scaling proprietary auction algorithms into connected television and streaming media platforms by 2028 would unlock a 35 billion dollar video advertising market. Solving streaming attribution inefficiencies would attract migrating linear television budgets, driving high-margin revenue acceleration past 30% and triggering significant institutional valuation multiple re-expansion.

Antitrust unbundling of mobile duopoly

Regulatory

25% probabilityStock price impact: +40.0%Earnings impact: Not quantified

Global regulatory mandates dismantling Google and Apple app store monopolies would allow independent billing and third-party app store execution. Bypassing 30% app store platform fees would dramatically lift developer net monetization, funneling billions in liberated marketing budgets directly into independent mediation auctions and supercharging operating cash flow.

Tail risks

Mobile runtime SDK telemetry prohibition

Regulatory

25% probabilityStock price impact: -45.0%Earnings impact: Not quantified

A coordinated operating system policy revision by Apple or Google banning third-party mediation SDKs or prohibiting real-time auction telemetry by 2027 would blind conversion models. Slashing return on ad spend would trigger immediate merchant budget flight, causing software platform revenues to contract by over 30% and crushing valuation multiples.

Antitrust forced mediation stack divestiture

Regulatory

22% probabilityStock price impact: -38.0%Earnings impact: Not quantified

Federal antitrust enforcement compelling the structural separation of MAX mediation from the proprietary DSP bidding engine would fracture closed-loop auction telemetry. Dismantling this integrated data feedback loop would compress operating margins toward commodity ad-network levels, destroying over a third of consolidated cash generation.

FICO:NYSEHQ:Listed:

Information Technology Β· Application Software

Fair Isaac Corporation provides analytics software in the Americas, Europe, the Middle East, Africa, and the Asia Pacific. It operates through two segments, Scores and Software.

RatingStrong Buy

Latest editorial review

Reviewed through 5 Oct 2026

Based on deep-analysis report: 20 Sept 2026 Β· newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

established lending relationships and expanding decision software provide earnings support while mortgage scoring competition challenges fee durability.

What to watch

The next results for lender adoption of rival scores and whether software growth offsets pressure on mortgage scoring fees.

+171.0%
Model rating: Buy
β€”Dividend yield (net)
β€”Buyback yield
18.4x
Price as of: 2026-10-02
52/100
34/100

Flagship insight

Credit Scoring Monopoly Confronts Regulatory Modernization While Enterprise Software Compounding Accelerates

Across specialized reports, there is high consensus that entrenched secondary securitization standards and accelerating enterprise cloud platform revenue protect core cash flows. However, sharp divergence remains regarding whether regulatory mortgage fee competition and elevated debt service will permanently compress future corporate operating margins.

The company faces a major shift as government housing regulators introduce new competition to lower credit scoring fees for home buyers. While headlines suggest the company could lose its dominant position, banks and mortgage bond investors rely heavily on its established formulas, making rapid replacement unlikely. Meanwhile, the company's high-margin cloud software business is growing rapidly, providing a reliable second engine of profits.

  • Wall Street bond investors require familiar credit scoring formulas, preventing mortgage lenders from quickly switching to cheaper alternatives.
  • Cloud-based fraud and decision-making software is growing rapidly, making the business far less dependent on mortgage fees alone.
  • Heavy borrowing used for past share buybacks now requires debt repayment, temporarily slowing down the pace of share repurchases.

Advisor consensus

Overall, advisors show very high price-direction agreement and low disagreement. Read on to see where advisor views still differ.

The primary disagreement across reports centers on whether the loss of regulatory mortgage exclusivity represents a permanent impairment of tollbooth economics or a manageable headline disruption. Bearish perspectives argue that recent earnings growth was an unsustainable artifact of aggressive price hikes that will reverse under sub-dollar competition, exacerbated by negative equity and rising debt service. Bullish analyses counter that secondary securitization lock-in and direct licensing will insulate cash flow while platform software ARR re-rates the business. This debate will resolve as early 2027 GSE loan delivery data reveals actual lender defection rates versus retained scoring volumes.

Risk and opportunity map

Longer-term opportunities

Secondary MBS covenants mandate next-generation scores

Competitive Positioning

35% probabilityStock price impact: +38.0%Earnings impact: Not quantified

Secondary mortgage-backed securities investors and credit rating agencies could formally reject uncalibrated rival scores, mandating next-generation trended FICO algorithms across agency pools by 2028. Triggered by early securitization default divergences, institutional asset managers would require proven predictive models in servicing contracts, fully restoring pricing hegemony and triggering an immediate multiple rerating.

Global banking agentic platform standardization

Innovation And Product

25% probabilityStock price impact: +32.0%Earnings impact: Not quantified

Tier-one global commercial banks could standardize enterprise-wide fraud mitigation and autonomous credit decisioning onto the cloud platform by 2029. Triggered by strict governance requirements around AI explainability, scaled multi-year consumption contracts would accelerate software annual recurring revenue past 1.5 billion dollars, permanently decoupling corporate valuation from domestic credit bureau controversies.

Tail risks

DOJ antitrust civil enforcement decree

Regulatory

28% probabilityStock price impact: -38.0%Earnings impact: Not quantified

The Department of Justice Antitrust Division could file a formal monopolization lawsuit challenging credit score pricing tiers and reseller distribution contracts by late 2027. A binding judicial consent decree capping wholesale scoring fees or mandating structural separation of scoring from software would decimate operating margins and permanently impair annual free cash flow.

Regulatory mandate of bi-merge reporting

Regulatory

32% probabilityStock price impact: -30.0%Earnings impact: Not quantified

Federal housing authorities could formally mandate a transition from tri-merge credit reports to a bi-merge standard by 2028 to lower consumer closing costs. Requiring only two bureau pulls per mortgage application would instantly cut aggregate industry scoring volume by one-third, severely contracting high-margin royalty revenue and exposing fixed balance-sheet debt burdens.

BKNG:NASDAQHQ:Listed:

Consumer Discretionary Β· Hotels, Resorts & Cruise Lines

Online travel company operating Booking.com, Priceline, Agoda, Kayak, and OpenTable across global travel and restaurant markets.

RatingStrong Buy

Latest editorial review

Reviewed through 5 Oct 2026

Based on deep-analysis report: 20 Sept 2026 Β· newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

a large travel marketplace turns repeat demand and direct bookings into cash without owning hotels.

What to watch

Weaker travel demand or rising marketing costs could reduce margins and the benefit from direct bookings.

+129.0%
Excl. dividends: +123.0%
0.6%Dividend yield (net)
β€”Buyback yield
17.0x
Price as of: 2026-10-02
73/100
65/100

Flagship insight

Asset-Light Cash Compounding Confronts Looming AI Disintermediation Tollbooth Risks

High consensus confirms exceptional asset-light cash conversion and aggressive share repurchases as primary equity drivers, while sharp divergence surrounds terminal artificial intelligence disintermediation risks, rising performance-marketing costs, and European regulatory take-rate caps over the five-year investment horizon.

Booking Holdings runs a powerful, asset-light travel network connecting millions of independent hotels with global travelers. The company spends very little on physical buildings, allowing it to convert about a third of its revenue into cash. Even though elevated fuel prices and fears of AI search engines have held down the stock's valuation, management uses its enormous cash flow to buy back and retire a large portion of its own shares each year, steadily boosting the value of each remaining share.

  • Over half of customers book directly through mobile apps, helping avoid expensive search engine advertising fees.
  • Large cash balances collected from traveler prepayments generate valuable interest income in a high-rate economic environment.
  • European regulations prevent strict rate guarantees, requiring the company to keep spending to attract travelers against hotel websites.

Advisor consensus

Overall, advisors show very high price-direction agreement and low disagreement. Read on to see where advisor views still differ.

The decisive disagreement centers on the terminal threat posed by artificial intelligence. One camp views generative AI as an existential disintermediation force that will bypass online aggregators via open protocols, justifying a depressed valuation multiple. The opposing camp proves that AI refers under 1% of room nights while actively deflating Booking's customer-service costs, viewing the platform as an essential settlement tollbooth. A secondary dispute involves balance-sheet risk: whether negative equity and $20.3 billion in gross debt constrain buybacks under higher interest rates, or whether negative working-capital float provides impregnable liquidity.

Risk and opportunity map

Longer-term opportunities

Autonomous Agent Travel Standard Monopoly

Innovation And Product

32% probabilityStock price impact: +36.0%Earnings impact: Not quantified

Leading frontier AI developers and mobile operating systems standardize on Booking's global merchant API as the exclusive backend execution engine for autonomous travel itineraries. Rather than disintermediating the platform, conversational assistants route millions of bookings through its infrastructure, eliminating billions in search ad spend, lifting operating margins past 40%, and driving dramatic multiple re-rating.

Middle East Energy Normalization Dividend

Macroeconomic And Macrofinancial

34% probabilityStock price impact: +24.0%Earnings impact: Not quantified

A comprehensive diplomatic resolution in the Persian Gulf restores maritime transit and depresses crude oil below $70 per barrel. Slashed jet-fuel costs allow airlines to restore intercontinental flight routes and reduce ticket surcharges, triggering an explosive global surge in high-margin cross-border tourism that lifts annual free cash flow toward $14 billion.

Tail risks

Frontier AI Direct Protocol Intermediation

Innovation And Product

25% probabilityStock price impact: -38.0%Earnings impact: Not quantified

Major tech platforms embed native booking protocols into smartphone operating systems, querying hotel property management systems directly and bypassing online travel agencies entirely. This technological bypass collapses top-of-funnel traffic, forcing Booking to wage destructive search-bidding wars, compressing operating margins below 25%, halving free cash flow, and permanently impairing terminal multiples.

Synchronized Stagflationary Travel Demand Freeze

Macroeconomic And Macrofinancial

22% probabilityStock price impact: -32.0%Earnings impact: Not quantified

Uncontained geopolitical energy shocks and protracted central-bank monetary tightening induce severe global stagflation, causing household discretionary leisure budgets to collapse. International room-night volume contracts by over 20%, turning operating leverage sharply negative, wiping out merchant working capital float, and forcing management to suspend buyback programs to protect liquidity.

NKE:NYSEHQ:Listed:

Consumer Discretionary Β· Footwear

Global sportswear company designing and marketing athletic footwear, apparel, equipment, and accessories for consumers worldwide.

RatingStrong Buy

Latest editorial review

Reviewed through 5 Oct 2026

Based on deep-analysis report: 20 Sept 2026 Β· newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

improved gross margin and lower overhead provide early support for a turnaround despite continuing weakness in direct sales.

What to watch

The next results for healthier full-price demand and whether falling digital sales or China weakness offset further margin improvement.

+144.0%
Excl. dividends: +132.0%
1.0%Dividend yield (net)
β€”Buyback yield
16.2x
Price as of: 2026-10-02
48/100
52/100

Flagship insight

Wholesale Channel Realignment Triggers Asymmetric Valuation Recovery Past Operational Trough

High consensus confirms that wholesale channel reconciliation and inventory cleansing have established an operational floor, while sharp divergence surrounds terminal operating margins and Chinese market recovery. Fortress balance sheet liquidity protects the dividend payout, whereas persistent import tariffs and specialty running rivals cap multiple re-expansion.

The central case for investing rests on an operational turnaround following a failed online-only experiment. The company hurt its business by neglecting retail store partners and overproducing retro sneakers, which damaged profits. Under veteran leadership, the business is repairing relationships with major sporting goods chains, clearing excess inventory, and refocusing on high-performance running shoes. While high tariffs and competition in China limit a complete return to past glory, stabilizing store sales and reducing clearance discounts will drive a powerful earnings rebound.

  • Restoring physical shelf space in major stores brings back high-volume sales without paying heavy digital marketing fees.
  • Rebuilding technical running shoes stops market share losses to boutique competitors and restores full-price customer purchases.
  • A rock-solid balance sheet with negligible net debt easily protects dividend payments while the business turnaround takes hold.

Advisor consensus

Overall, advisors show very high price-direction agreement and low disagreement. Read on to see where advisor views still differ.

The decisive analytical disagreement centers on Nike's normalized mid-cycle operating margin ceiling and terminal growth profile. Optimistic frameworks project operating margins surging past 12.5% on aggressive wholesale leverage and rapid Chinese demand recovery. Conversely, forensically grounded perspectives emphasize that underlying fiscal 2026 margins sat near 6% when stripping out the 986 million dollar tariff refund, arguing that permanent China share erosion and specialty running competition cap recovery near 10% to 11%. Resolving this debate requires tracking gross margins excluding tariff credits alongside North American wholesale sell-through rates across upcoming fiscal 2027 quarters.

Risk and opportunity map

Longer-term opportunities

Mega-Event Sports Marketing Dominance Cycle

Competitive Positioning

35% probabilityStock price impact: +32.0%Earnings impact: Not quantified

Unprecedented brand prominence across the upcoming 2028 Los Angeles Olympics and global athletic championships could trigger a worldwide consumer demand supercycle. If proprietary performance footwear sweeps marathon and sprint podiums, viral cultural resonance would re-establish undisputed athletic supremacy. This halo effect would drive double-digit full-price wholesale restocking globally, though execution risk caps realization probability at 35%.

Bilateral Footwear Tariff Exemption Breakthrough

Regulatory

28% probabilityStock price impact: +28.0%Earnings impact: Not quantified

A comprehensive diplomatic trade resolution between Washington and Southeast Asian trade partners could grant targeted tariff exemptions on imported athletic footwear by late 2027. Eliminating replacement import duties would directly remove over one billion dollars in annualized customs friction, dropping straight to operating profit. Bipartisan protectionist consensus keeps realization probability below fifty percent at 28%.

Tail risks

Southeast Asian Manufacturing Supply Fracture

Operational Efficiency

24% probabilityStock price impact: -34.0%Earnings impact: Not quantified

Severe geopolitical escalation or localized climate disruptions across Vietnam and Indonesia could shutter major contract footwear assembly clusters for several months. With more than half of footwear production concentrated in this narrow corridor, prolonged factory halts would trigger catastrophic inventory stockouts during peak retail seasons. Geographic diversification and safety inventory buffering keep this tail risk probability at 24%.

Dividend Coverage Fracture and Distribution Freeze

Capital Allocation

22% probabilityStock price impact: -26.0%Earnings impact: Not quantified

If fiscal 2027 free cash flow stagnates below 2.0 billion dollars while dividend distributions demand 2.4 billion, management could be forced to freeze or reduce the payout to preserve liquidity. Breaking a twenty-four-year increase streak would trigger mechanical selling from income-mandated funds and shatter institutional confidence. Management's resolve to defend the payout keeps probability at 22%.

The leading five

The Top 5

#5 β†’ #1

Five ideas remain. Each passed the full editorial review and earned a place in this edition's highest-conviction group.

TTD:NASDAQHQ:Listed:

Communication Services Β· Advertising

Technology platform for buyers of advertising enabling data-driven digital advertising campaigns across channels.

RatingStrong Buy

Latest editorial review

Reviewed through 5 Oct 2026

Based on deep-analysis report: 20 Sept 2026 Β· newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

independent advertising infrastructure benefits from demand for measurable campaigns outside the largest closed platforms.

What to watch

Changes to identity tracking could weaken targeting effectiveness and push advertising budgets toward closed platforms.

+252.0%
Model rating: Buy
β€”Dividend yield (net)
β€”Buyback yield
13.8x
Price as of: 2026-10-02
65/100
29/100

Flagship insight

Independent Ad Tech Tollbooth Rebuilds Cash Engine After Historic Valuation Capitulation

Across independent research reports, high consensus emerges that massive free cash flow, debt-free liquidity, and aggressive share repurchases anchor enterprise valuation after extreme capitulation. The primary driver centers on connected television volume expansion, while the decisive friction remains competitive take-rate compression from dominant retail media ecosystems.

The company has fallen sharply in market value because advertisers paused spending and big tech rivals offered steep discounts. However, the business behaves like a toll bridge for digital television ads, generating massive cash without carrying dangerous debt. Recent cost cuts and steady streaming demand should help profit recover over time, turning panic-driven price drops into a solid long-term opportunity.

  • Heavy cash generation allows the company to buy back cheap shares and boost future value per share.
  • Shifting software to private data centers creates temporary accounting costs but lowers future transaction expenses permanently.
  • Neutral ad buying keeps major television streaming networks loyal rather than surrendering viewer data to rivals.

Advisor consensus

Overall, advisors show very high price-direction agreement and low disagreement. Read on to see where advisor views still differ.

The central disagreement across research reports centers on whether recent financial deceleration reflects cyclical advertising budget pauses or structural take-rate erosion from walled gardens. Optimistic views assume gross platform spend remains durable and project rapid multiple re-expansion as restructuring charges fade and buybacks shrink the float. Conversely, skeptical assessments argue that heavy stock-based compensation dilutes owner earnings and that onshored data-center depreciation permanently hardens fixed costs. Resolving this debate requires observing whether fourth-quarter revenue guidance stabilizes alongside positive sequential operating margin expansion without further agency fee concessions.

Risk and opportunity map

Longer-term opportunities

Mandated Google ad tech divestiture

Regulatory

32% probabilityStock price impact: +60.0%Earnings impact: Not quantified

Federal antitrust litigation could reach a final judicial remedy ordering the structural divestiture of Google's publisher ad server and ad exchange by 2028. Decoupling sell-side auction tools from buy-side software would eliminate self-preferencing, redirecting billions in displaced advertiser budgets toward independent platforms. This discrete unlock would expand addressable bidding inventory and prompt an aggressive multiple re-rating.

Exclusive tier-one streaming programmatic mandate

Competitive Positioning

26% probabilityStock price impact: +48.0%Earnings impact: Not quantified

A dominant global streaming network could abandon proprietary ad-tech development and designate the platform as its exclusive programmatic buying gateway by late 2027. Unlocking tens of billions of biddable, high-CPM video impressions would instantly reaccelerate revenue growth past twenty percent annually. High incremental software margins would expand cash generation, driving substantial valuation upside.

Tail risks

Sovereign ban on cross-domain identifiers

Regulatory

25% probabilityStock price impact: -45.0%Earnings impact: Not quantified

Regulatory authorities in the United States and Europe could coordinate an outright ban on pseudonymous hashed identifiers like UID2 by 2028, classifying them as non-consensual tracking. This intervention would sever programmatic targeting graphs across the open web, sharply degrading campaign measurement. Brand advertisers would retreat into closed walled gardens, causing platform revenue to contract and permanently compressing cash flow.

Streaming and retail media consortium foreclosure

Competitive Positioning

22% probabilityStock price impact: -40.0%Earnings impact: Not quantified

Major streaming platforms and retail media networks could form closed bilateral alliances by 2027, completely restricting programmatic access to proprietary demand-side tools. Bypassing independent software intermediaries would sever access to premium connected television inventory. Platform transaction volume would plunge, reversing operating leverage into acute margin deterioration and locking the equity into a distressed valuation multiple.

PRCT:NASDAQHQ:Listed:

Health Care Β· Health Care Equipment

Medical technology company developing robotic systems for Aquablation therapy to treat benign prostatic hyperplasia.

RatingStrong Buy

Latest editorial review

Reviewed through 5 Oct 2026

Based on deep-analysis report: 20 Sept 2026 Β· newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

robotic treatment can broaden access to less invasive prostate procedures as hospital adoption expands.

What to watch

Slower hospital installations or lower procedure utilization could delay cash generation and widen funding needs.

+272.0%
Model rating: Strong Buy
β€”Dividend yield (net)
β€”Buyback yield
N/M
Price as of: 2026-10-02
54/100
30/100

Flagship insight

Hidden Surgical Consumable Annuity Set to Overcome Hospital Channel Inventory Reset

There is high consensus that clinical demand remains robust beneath transient channel destocking, driven by recurring waterjet consumable utilization and gross margins reaching 66%. However, sharp divergence persists regarding the five-year cash-burn runway, debt refinancing risks, and regulatory oncology timing.

This company makes advanced robotic systems that use high-speed waterjets to treat enlarged prostates without heat, protecting patients from surgical complications. The stock plunged because the former management team used aggressive discounts to push excess parts into hospital storage closets, making sales look artificially high. Now that hospitals have used up that extra inventory, real surgical demand is shining through, with actual surgeries growing over 20%. Because every surgery requires a new, high-profit disposable handpiece, each robot placed in a hospital acts like a recurring cash tollway. As surgery volumes grow and research spending winds down, the company is on track to stop losing money and become self-funding.

  • Surgeries are growing steadily, proving doctors prefer this waterjet technology over older, riskier heating techniques.
  • Recurring sales of single-use surgical parts make up the majority of revenue, creating reliable ongoing cash.
  • Ample cash in the bank provides enough breathing room to reach profitability without needing emergency loans.

Advisor consensus

Overall, advisors show very high price-direction agreement and low disagreement. Read on to see where advisor views still differ.

The primary analytical disagreement across reports concerns the velocity of operating leverage and the severity of financing dilution. One group argues that customer inventory destocking is already complete, with 66% gross margins and 21% procedure growth providing a clear, self-funded path to positive cash flow by 2028 without secondary dilution. Conversely, the more skeptical group demonstrates that trailing cash burn of $85 million to $126 million leaves barely five quarters of liquidity before 2027 debt obligations, making a dilutive financing round highly probable. This debate will be resolved by observed fourth-quarter 2026 cash conversion and the gross margin trajectory excluding one-off tariff refunds.

Risk and opportunity map

Longer-term opportunities

WATER IV pivotal oncology trial breakthrough

Innovation And Product

34% probabilityStock price impact: +75.0%Earnings impact: Not quantified

Primary readouts from the randomized WATER IV trial in spring 2027 demonstrate Aquablation's non-inferior oncologic resection and dramatically superior continence and sexual preservation compared to radical prostatectomy. Expedited FDA oncology clearance by late 2028 would double the addressable surgical market, driving aggressive robot placements and high-margin consumable pull-through across comprehensive cancer centers.

Strategic takeover by diversified medtech conglomerate

Competitive Positioning

24% probabilityStock price impact: +60.0%Earnings impact: Not quantified

A major surgical device conglomerate such as Boston Scientific, Stryker, or Johnson & Johnson launches an outright takeover offer between 2027 and 2028. An acquirer could immediately eliminate redundant commercial selling infrastructure, resolve litigation liabilities, and cross-sell the 1,000-unit installed robotic base globally, paying an immediate transaction premium over depressed public valuations.

Tail risks

Emergency discounted secondary equity offering

Capital Allocation

30% probabilityStock price impact: -42.0%Earnings impact: Not quantified

If procedural growth falters below 10% while trailing operational cash burn persists above $30 million quarterly into late 2027, available cash reserves will drop below prudent thresholds. Management would be forced to execute a deeply discounted equity secondary offering into a depressed tape, heavily diluting existing common equity holders by more than 25%.

WATER IV trial oncologic efficacy failure

Innovation And Product

28% probabilityStock price impact: -40.0%Earnings impact: Not quantified

Intermediate clinical data from the WATER IV trial in 2027 reveals unacceptable positive surgical margins or elevated cancer recurrence compared to radical prostatectomy. Clinical failure irrevocably bars Aquablation from the multi-billion-dollar localized prostate cancer market, triggering severe sell-side target reductions and permanently confining the platform to benign prostatic hyperplasia.

The finalists

The Top 3

#3 β†’ #1

The shortlist is over. These three stocks earned the strongest conviction in this edition. Count down to the research team's number-one pick.

Checking your access...

The winner

The Number-One Pick

The edition's highest-conviction selection, combining near-term opportunity with long-term confirmation.

Market context and selection approach

Markets remain selective, so this review emphasizes earnings delivery, competitive position, capital needs, and the next operating milestones. Current evidence can support a thesis while still leaving meaningful company, policy, liquidity, or macro risk.

The list favors the strongest supported investment cases in priority order and stops when enough qualifying opportunities are available; price movements alone do not determine whether a case remains credible.

References

Frozen links are separated into editorial-review evidence, 5–6 global-context references, and 3–4 governed Researcher citations per selected asset. Duplicate URLs appear once; the combined citation list is capped at 30.

A. Editorial-review sources

  1. 1.Intuit Inc - frozen Batch 7 consensus research iPulse AI Β· SPECIALIST SECONDARY Β· 21 Sept 2026, 07:13 UTChttps://ipulseai.com/stocks/intuit-intuReviewed for: Intuit Inc (INTU.NASDAQ)
  2. 2.Adobe Inc. - frozen Batch 7 consensus research iPulse AI Β· SPECIALIST SECONDARY Β· 21 Sept 2026, 07:13 UTChttps://ipulseai.com/stocks/adobe-adbeReviewed for: Adobe Inc. (ADBE.NASDAQ)
  3. 3.RxSight Inc - frozen Batch 7 consensus research iPulse AI Β· SPECIALIST SECONDARY Β· 21 Sept 2026, 07:13 UTChttps://ipulseai.com/stocks/rxsight-rxstReviewed for: RxSight Inc (RXST.NASDAQ)
  4. 4.PROCEPT BioRobotics - frozen Batch 7 consensus research iPulse AI Β· SPECIALIST SECONDARY Β· 21 Sept 2026, 07:13 UTChttps://ipulseai.com/stocks/procept-biorobotics-prctReviewed for: PROCEPT BioRobotics (PRCT.NASDAQ)
  5. 5.The Trade Desk, Inc. - frozen Batch 7 consensus research iPulse AI Β· SPECIALIST SECONDARY Β· 21 Sept 2026, 07:13 UTChttps://ipulseai.com/stocks/trade-desk-ttdReviewed for: The Trade Desk, Inc. (TTD.NASDAQ)
  6. 6.NIKE Reports Fiscal 2027 First Quarter Results NIKE Β· ISSUER RELEASE Β· 1 Oct 2026, 00:00 UTChttps://investors.nike.com/investors/news-events-and-reports/investor-news/investor-news-details/2026/NIKE-Inc--Reports-Fiscal-2027-First-Quarter-Results/default.aspxReviewed for: NIKE, Inc. (NKE.NYSE)
  7. 7.Booking Holdings Inc - frozen Batch 7 consensus research iPulse AI Β· SPECIALIST SECONDARY Β· 21 Sept 2026, 07:13 UTChttps://ipulseai.com/stocks/booking-holdings-bkngReviewed for: Booking Holdings Inc (BKNG.NASDAQ)
  8. 8.Fannie Mae Announces Simplified Pricing Across Credit Score Models Fannie Mae Β· REGULATOR Β· 30 Sept 2026, 00:00 UTChttps://capitalmarkets.fanniemae.com/mortgage-backed-securities/simplified-pricing-across-credit-score-modelsReviewed for: Fair Isaac Corporation (FICO.NYSE)
  9. 9.Applovin Corp - frozen Batch 7 consensus research iPulse AI Β· SPECIALIST SECONDARY Β· 21 Sept 2026, 07:13 UTChttps://ipulseai.com/stocks/applovin-appReviewed for: Applovin Corp (APP.NASDAQ)
  10. 10.Boston Scientific Corporation - frozen Batch 7 consensus research iPulse AI Β· SPECIALIST SECONDARY Β· 21 Sept 2026, 07:13 UTChttps://ipulseai.com/stocks/boston-scientific-bsxReviewed for: Boston Scientific Corporation (BSX.NYSE)

B. Global market context

These dated files capture broader market, macroeconomic, policy, and cross-asset context. Each frozen file is supplied as input to every advisor model during deep analysis; its citations never count toward an asset-specific minimum.

This original edition uses the frozen global-context evidence embedded in each linked deep analysis; no separate post-analysis market-context review was added.

C. Asset-specific deep-analysis sources

Captured by governed AI Researcher agents. Shared URLs are shown once and identify every selected asset they support.

Asset-specific Researcher citations remain available in each linked deep analysis above; this original edition did not add a second citation set.

Important information

Research scope and investor notice

Research scope

  • Newer dated external evidence is NOT_RETAINED for assets without a newly opened primary source; evidenceRefs identify retained earlier documents or exact frozen consensus research.
  • Current event searches are incomplete and cannot establish the absence of all developments; VALID denotes the strict retained-thesis state, not comprehensive current-news assurance.
  • Undated protocol documentation was checked as context without inventing publication dates; issuer targets and research scenarios remain forward-looking.

Investor notice

AI-assisted editorial analysis. Reviewed and approved by Russlan Ramdowar. Published by Future Edge Group FZE. This is general research, not personalized investment advice.

Forecasts, ratings, and return estimates are uncertain and may change as new evidence becomes available.