Assets

iPulse AI Editorial Picks research

Stocks To Avoid For Now

See which stocks to avoid for now using iPulse AI's cross-horizon investment research. The analysis requires both the one-year and five-year outlooks to support caution, then examines earnings quality, cash flow, balance-sheet pressure, valuation, business risks and the evidence that could disprove the downside case. Each stock includes a clear thesis and the warning signs investors should monitor.

Explore overall iPulse AI portfolio strategies and performance

Editorial ApproverRusslan Ramdowar iPulse AI Engine V6 15 min read
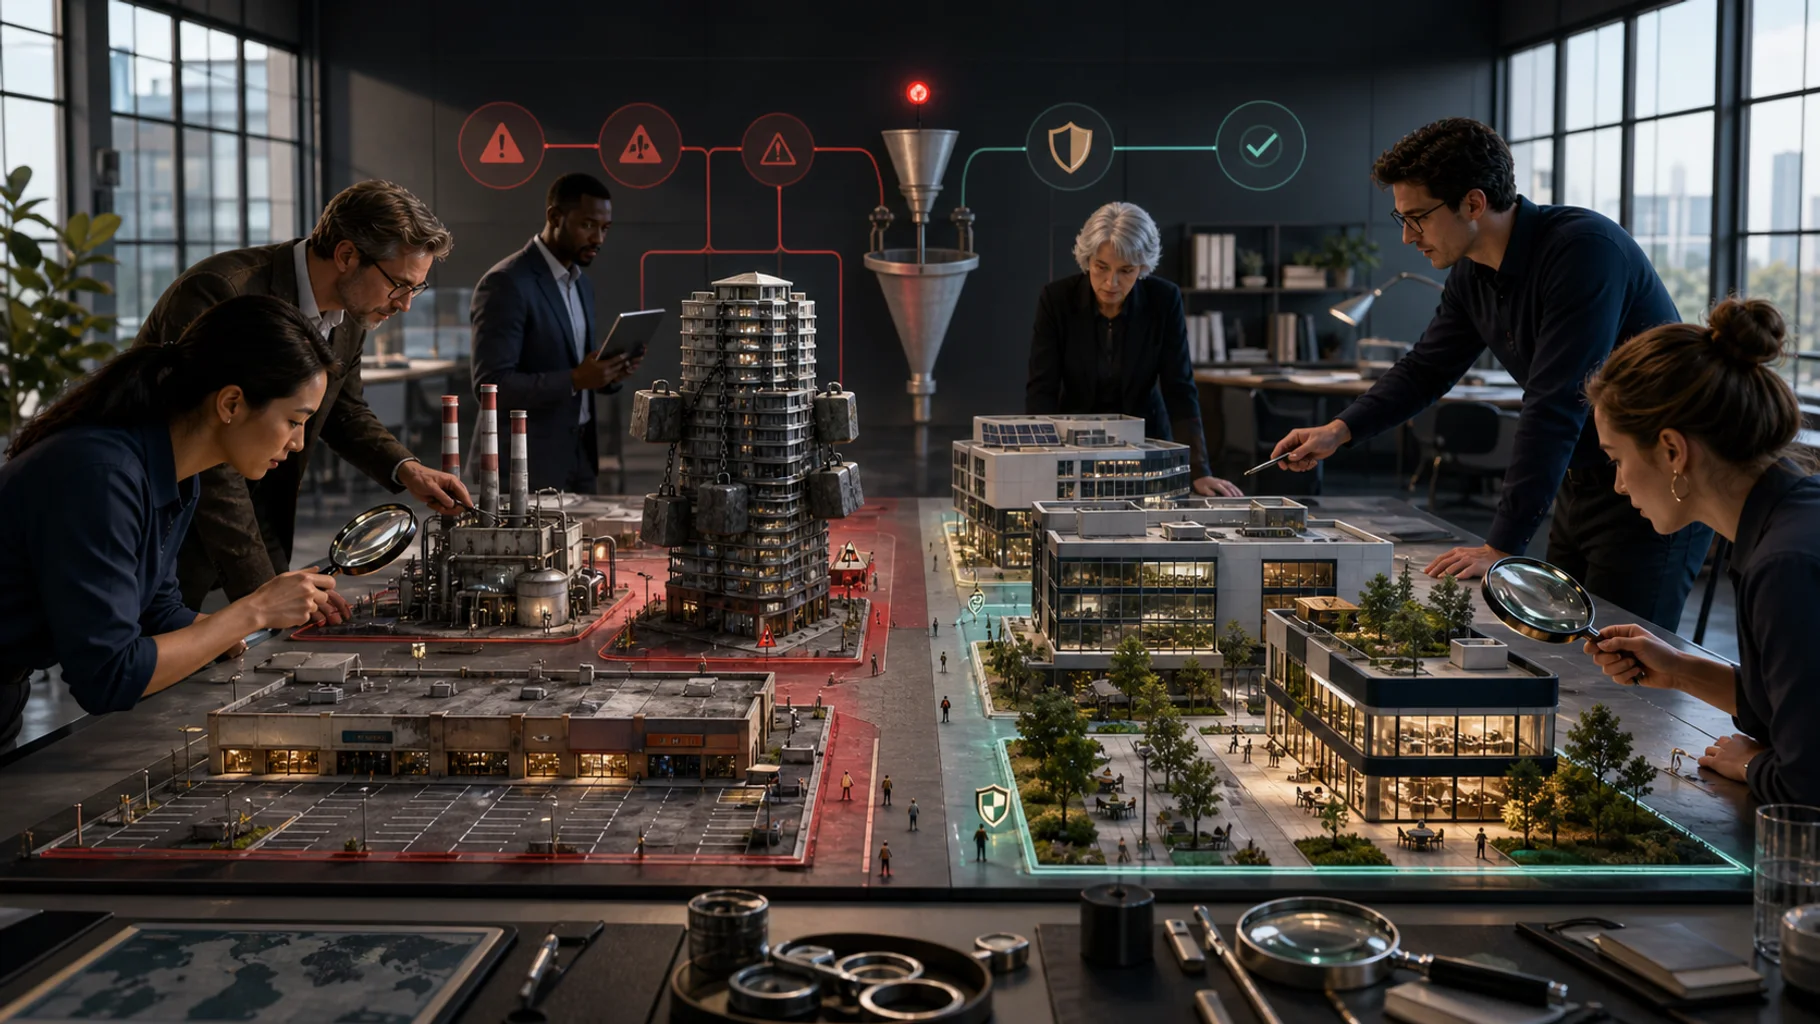
Institutional analysts inspect miniature business ecosystems and separate structurally weak companies from resilient businesses using evidence and risk controls.

Our Approach: The broad screening universe covers about 100,000 stocks; it is not the number of assets with published forecasts. For this edition, 376 assets passed preselection and underwent deep multi-agent analysis. iPulse AI Engine V6 ranked the top 10, and 10 Editorial Top Picks passed the separate evidence review and approval workflow. Read the detailed methodology

Editorial Picks countdown

Top 10 Editorial Picks to Avoid

SOUN:NASDAQHQ:Listed:

Information Technology Β· Application Software

Voice AI platform providing speech recognition and natural language understanding for automotive, IoT, and smart devices.

RatingSell All

Latest editorial review

Reviewed through 24 Aug 2026

Based on deep-analysis report: 5 Jul 2026 Β· newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

The editor's view

The original investment case and current rating remain supported as of 2026-08-24T15:12:25Z. Record revenue and higher outlook are counter-evidence, but do not yet resolve valuation, cash-flow, concentration, and execution risk across both horizons. Monitor the next material filing, policy decision, protocol release, or operating update.

What to watch

The main risk to the avoid view is a durable improvement in cash generation, funding needs, and execution that persists beyond one quarter. Watch for several reporting periods of durable cash-flow, funding, and execution improvement that could disprove the avoid case.

-4.3%
Model rating: Partially Sell
β€”Dividend yield (net)
β€”Buyback yield
Unavailable
54/100
6/100

Flagship insight

Why This High-Growth Voice AI Pioneer Faces A Severe Valuation Reset

There is sharp divergence across reports regarding whether this voice AI provider can successfully integrate its latest enterprise acquisitions. While top-line expansion remains robust, escalating compute costs and persistent shareholder dilution present severe structural headwinds, threatening multiple compression under a restrictive macroeconomic regime.

This company is trying to grow quickly by buying other businesses, but this strategy is creating big challenges. While these purchases help the company gain new customers, they also bring heavy debt and require printing a lot of new stock, which lowers the value of existing shares. In a tough economy with high interest rates, the company must prove it can actually make a profit rather than just showing fast sales growth.

  • Buying other companies makes sales look like they are growing fast, but it hides the high costs of combining these businesses.
  • Running advanced voice AI systems requires massive computer power, which is eating into the company's profit margins.
  • The company is constantly printing and selling new shares to raise cash, which dilutes the value for current everyday investors.
  • Many carmakers and restaurants prefer independent software over big tech, giving this company a temporary advantage in those areas.
  • High interest rates make unprofitable companies less attractive to major investors, putting downward pressure on the stock price.
  • Recent departures of top financial officers and selling by company insiders raise important warning flags for retail buyers.

Advisor consensus

Overall, advisor direction is mixed, with meaningful disagreement. Read on to see where advisor views still differ.

The primary disagreement across reports centers on the company's long-term survival and the viability of its acquisition strategy. Optimistic views argue that buying legacy enterprise platforms is a highly efficient distribution shortcut that will accelerate free cash flow breakeven by 2028. Conversely, skeptical analyses interpret the aggressive M&A roll-up as a desperate attempt to mask organic customer churn and decaying intellectual property. There is also significant debate regarding whether the company's edge-integration capabilities can withstand the rapid technological convergence of native multimodal models from frontier labs.

Risk and opportunity map

What could improve the case

Strategic Takeover by Tech or Auto Giant

Competitive Positioning

25% probabilityStock price impact: +80.0%Earnings impact: Not quantified

A major technology firm, semiconductor giant, or legacy automotive OEM looking to secure independent voice AI infrastructure and data sovereignty could acquire the company outright. This consolidation event would trigger an immediate, massive acquisition premium, neutralizing standalone cash-burn risks for current shareholders and closing the technological displacement risk entirely.

Accelerated Free Cash Flow Breakeven

Operational Efficiency

20% probabilityStock price impact: +50.0%Earnings impact: Not quantified

If the integration of recent acquisitions executes flawlessly, generating unexpected operational leverage and rapid cross-selling synergies, the company could achieve positive free cash flow ahead of schedule. Crossing this profitability threshold would trigger a profound institutional rerating, attracting capital that previously avoided the stock due to cash-burn risks.

Key frictions and downside risks

Native Audio Model Commoditization

Innovation And Product

40% probabilityStock price impact: -70.0%Earnings impact: Not quantified

A major frontier AI lab could release a free or heavily subsidized, zero-latency enterprise voice API that natively processes audio. This technological shift would instantly commoditize the standalone voice recognition layer, causing massive enterprise customer churn, permanently destroying the company's pricing power, and rendering its independent moat irrelevant.

Liquidity Exhaustion and Distressed Restructuring

Capital Allocation

35% probabilityStock price impact: -65.0%Earnings impact: Not quantified

If the cash burn accelerates during a complex integration phase while public equity markets reject further dilutive offerings, the company could hit a liquidity wall. Unable to secure favorable financing in a restrictive macro environment, it could face distressed restructuring, severely impairing or completely diluting common equity holders.
HIMS:NYSEHQ:Listed:

Health Care Β· Health Care Services

Hims & Hers Health, Inc. operates as a consumer-first health and wellness platform that connects consumers to licensed healthcare professionals in the United States, the United Kingdom, Canada, Germany.

RatingSell All

Latest editorial review

Reviewed through 24 Aug 2026

Based on deep-analysis report: 5 Jul 2026 Β· newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

The editor's view

The original investment case and current rating remain supported as of 2026-08-24T15:12:25Z. The quarter provides current growth evidence, but regulatory, product, and valuation risks remain sufficient to retain the dual-horizon caution. Monitor the next material filing, policy decision, protocol release, or operating update.

What to watch

The main risk to the avoid view is a durable improvement in cash generation, funding needs, and execution that persists beyond one quarter. Watch for several reporting periods of durable cash-flow, funding, and execution improvement that could disprove the avoid case.

-15.5%
Model rating: Partially Sell
β€”Dividend yield (net)
β€”Buyback yield
Unavailable
47/100
15/100

Flagship insight

How Regulatory Shifts and Margin Compression Are Reshaping Digital Healthcare Platforms

There is high consensus that the platform faces severe structural headwinds as regulatory loopholes close. While international acquisitions temporarily mask organic deceleration, the forced transition from high-margin compounded treatments to low-margin branded distribution permanently impairs unit economics, escalating customer acquisition costs and leverage under restrictive monetary conditions.

The company is going through a difficult shift from a fast-growing online health brand to a standard digital pharmacy. In the past, the company made high profits by selling custom-made weight-loss drugs during shortages. Now, as those shortages end and government rules tighten, they must sell brand-name drugs instead, which are much less profitable. At the same time, finding new customers is becoming more expensive, and the company has taken on significant debt to buy international businesses, making its financial position much riskier.

  • Government rules are closing the loophole that allowed the company to sell cheap, custom-made weight-loss drugs.
  • Selling brand-name drugs instead of custom ones means much lower profit margins and higher costs for the business.
  • Finding new customers online is getting harder and more expensive due to changes in search engines and rising competition.
  • The company has taken on a large amount of debt to buy international companies, which increases financial risk.
  • Older product lines like hair loss and sexual health treatments remain steady but cannot make up for the weight-loss slowdown.
  • Everyday investors should watch whether the company can keep its current subscribers without spending too much on advertising.

Advisor consensus

Overall, advisors show very high price-direction agreement and low disagreement. Read on to see where advisor views still differ.

The primary disagreement across the reports centers on the long-term viability of the company's infrastructure pivot. Some perspectives argue that the massive capital expenditures and international acquisitions represent a visionary transition toward a vertically integrated, global platform with a durable physical moat. Conversely, other views interpret these moves as defensive, value-destroying empire-building designed to mask organic domestic stagnation. There is also disagreement regarding the stickiness of the subscriber base when transitioning from heavily discounted compounded drugs to expensive branded alternatives.

Risk and opportunity map

What could improve the case

Strategic Acquisition by Healthcare or Tech Major

Competitive Positioning

25% probabilityStock price impact: +35.0%Earnings impact: Not quantified

As the valuation multiple compresses, the company's active subscriber base and digital front-door infrastructure could make it an attractive acquisition target for legacy pharmacy chains, insurers, or tech giants looking for a turnkey direct-to-consumer health platform, providing a sudden premium buyout exit for shareholders.

Proprietary AI Diagnostic Platform Launch

Innovation And Product

15% probabilityStock price impact: +35.0%Earnings impact: Not quantified

Successfully commercializing a proprietary, regulatory-approved AI diagnostic and triage platform could allow the company to transition from a low-margin distributor to a high-margin software provider, radically resetting operating efficiency, lowering provider costs to near zero, and rebuilding a highly defensible technological moat.

Key frictions and downside risks

Complete FDA Compounding Ban

Regulatory

40% probabilityStock price impact: -45.0%Earnings impact: Not quantified

The FDA could issue a blanket prohibition or intense crackdown on compounded peptides and other personalized formulations. This would instantly nuke the company's highest-growth segments, triggering massive subscriber churn, class-action lawsuits over marketing claims, and catastrophic write-downs of newly built physical compounding infrastructure.

Debt Refinancing and Liquidity Crisis

Macroeconomic And Macrofinancial

30% probabilityStock price impact: -40.0%Earnings impact: Not quantified

If structural unprofitability persists and cash burn accelerates, the heavy debt load could trigger covenant breaches. In a tight-liquidity environment, the company would face punitive refinancing terms or highly dilutive equity raises, severely impairing shareholder value and potentially leading to a distressed restructuring of the capital structure.

RGTI:NASDAQHQ:Listed:

Information Technology Β· Electronic Equipment & Instruments

Quantum computing company developing superconducting quantum processors, cloud access, and full-stack quantum computing systems.

RatingSell All

Latest editorial review

Reviewed through 24 Aug 2026

Based on deep-analysis report: 5 Jul 2026 Β· newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

The editor's view

The original investment case and current rating remain supported as of 2026-08-24T15:12:25Z. The update refreshed technical progress and liquidity, but does not yet resolve commercialization, dilution, and execution risks behind the avoid case. Monitor the next material filing, policy decision, protocol release, or operating update.

What to watch

The main risk to the avoid view is a durable improvement in cash generation, funding needs, and execution that persists beyond one quarter. Watch for several reporting periods of durable cash-flow, funding, and execution improvement that could disprove the avoid case.

-20.4%
Model rating: Partially Sell
β€”Dividend yield (net)
β€”Buyback yield
Unavailable
46/100
3/100

Flagship insight

Why Speculative Capital Is Flowing Into Geopolitically Protected Deep Tech Infrastructure

There is high consensus that this pre-commercial hardware developer functions as a geopolitically protected sovereign asset, yet faces severe valuation headwinds. While its fortress balance sheet provides a multi-year survival runway, structural cash burn and alternative computing modalities present acute long-term displacement risks for equity holders.

This quantum computing company is a highly speculative stock that behaves like a lottery ticket. While the company has a massive cash pile that will keep it running for several years, it is currently losing a lot of money and struggling to grow its actual sales. The general public is excited about the future of quantum technology, but the company faces tough competition from tech giants like Google and Microsoft, who have much more money to spend on research.

  • A huge cash reserve of over five hundred million dollars protects the company from going bankrupt anytime soon.
  • Government defense contracts and grants provide a steady lifeline because the U.S. wants to keep quantum technology domestic.
  • The company loses money on every system it builds due to high cooling and manufacturing costs.
  • Big upcoming stock market listings from other major tech firms could pull investor money away from this stock.
  • Other quantum technologies might prove better and cheaper, making this company's hardware obsolete.
  • Investors face continuous risk of stock dilution as the company issues new shares to fund its expensive research.

Advisor consensus

Overall, advisors show high price-direction agreement with limited disagreement. Read on to see where advisor views still differ.

The primary disagreement across the reports centers on the company's long-term survival and commercialization timeline. Bullish perspectives emphasize the structural advantages of owning a dedicated fabrication facility and the security of a massive cash runway, arguing these factors will allow the firm to successfully transition to a high-margin cloud-access model. Conversely, bearish views argue that the superconducting architecture is fundamentally flawed due to thermodynamic limits, meaning the massive capital expenditures represent unrecoverable wealth destruction. There is also divergence regarding the impact of government grants, with some viewing them as a solid valuation floor and others as a source of punitive dilution.

Risk and opportunity map

What could improve the case

Commercial Fault-Tolerance Breakthrough

Innovation And Product

10% probabilityStock price impact: +150.0%Earnings impact: Not quantified

The company unexpectedly achieves a verified breakthrough in quantum error correction years ahead of schedule, transitioning the technology to enterprise-ready utility and unlocking high-margin cloud revenue streams.

Strategic Hyperscaler Acquisition

Competitive Positioning

15% probabilityStock price impact: +75.0%Earnings impact: Not quantified

A major cloud provider or defense prime acquires the company outright to secure its proprietary fabrication facility and patent portfolio, delivering a massive strategic premium to existing shareholders.

Key frictions and downside risks

Capital Market Lockout

Macroeconomic And Macrofinancial

40% probabilityStock price impact: -80.0%Earnings impact: Not quantified

Under sustained macroeconomic stress, public markets lose patience with pre-profit narratives, shutting the equity issuance window and forcing a highly punitive restructuring or bankruptcy as cash reserves deplete.

Architectural Obsolescence

Innovation And Product

35% probabilityStock price impact: -70.0%Earnings impact: Not quantified

A competitor utilizing a different quantum modality achieves definitive commercial supremacy, instantly rendering the company's superconducting hardware stack and fabrication investments worthless.

VSXY:NYSEHQ:Listed:

Consumer Discretionary Β· Apparel Retail

Specialty retailer focused on intimate apparel, beauty, and lifestyle products under the Victoria's Secret and Pink brands.

RatingSell All

Latest editorial review

Reviewed through 24 Aug 2026

Based on deep-analysis report: 5 Jul 2026 Β· newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

The editor's view

The original investment case and current rating remain supported as of 2026-08-24T15:12:25Z. The scheduled earnings update did not provide completed evidence sufficient to reverse the dual-horizon caution; demand and margin repair remain unproven. Monitor the next material filing, policy decision, protocol release, or operating update.

What to watch

The main risk to the avoid view is a durable improvement in cash generation, funding needs, and execution that persists beyond one quarter. Watch for several reporting periods of durable cash-flow, funding, and execution improvement that could disprove the avoid case.

-35.2%
Model rating: Partially Sell
β€”Dividend yield (net)
β€”Buyback yield
34.4x
36/100
29/100

Flagship insight

Why Delayed Supply Chain Accounting Is Masking A Major Retail Valuation Trap

High consensus across reports reveals that a temporary margin expansion is masking severe structural vulnerabilities. While near-term cash flows remain resilient, impending maritime freight shocks, high financial leverage, and intense digital competition present severe headwinds, threatening a material valuation repricing as delayed supply-chain costs hit the income statement.

The main story here is that the recent stock price jump is likely a temporary boost rather than a permanent turnaround. While the company has improved its marketing and bought back a lot of its own shares to boost short-term numbers, it still faces huge challenges. High debt, rising shipping costs, and tough competition from fast-moving online brands mean that profits are likely to shrink in the coming months, making the stock highly risky for everyday investors.

  • Rising shipping rates and packaging costs will soon eat into profits as newer, more expensive inventory arrives.
  • The company carries a heavy debt load, which becomes much more expensive to manage in today's high-interest-rate environment.
  • Big spending on buying back stock helps the price now but leaves less cash to upgrade older physical stores.
  • Younger shoppers are increasingly choosing faster, online-only competitors that can design and deliver new styles much quicker.
  • The current high stock valuation leaves no room for error, meaning any disappointing sales report could trigger a sharp drop.
  • International growth, especially in overseas markets, provides a helpful cushion but cannot fully save the business from domestic slowdowns.

Advisor consensus

Overall, advisors show high price-direction agreement with limited disagreement. Read on to see where advisor views still differ.

The primary disagreement across reports centers on the durability of the brand's turnaround and the timing of margin compression. Some analyses assume that the brand repositioning and digital integrations have structurally improved pricing power, allowing the company to sustain higher margins over a longer horizon. Conversely, more bearish perspectives argue that these gains are purely cyclical and will be rapidly undone by immediate supply chain cost shocks. There is also disagreement regarding the risk weighting of the company's debt, with some viewing it as a manageable liability and others as an imminent refinancing threat.

Risk and opportunity map

What could improve the case

Private Equity Take-Private Buyout

Capital Allocation

20% probabilityStock price impact: +30.0%Earnings impact: Not quantified

If the public market multiple compresses excessively while free cash flow remains positive, the company's strong cash generation and brand IP could attract a leveraged buyout. A private equity sponsor could take the firm private to optimize operations away from public scrutiny, triggering an immediate premium for shareholders.

Strategic Digital Asset Spin-Off

Capital Allocation

15% probabilityStock price impact: +25.0%Earnings impact: Not quantified

An activist investor could successfully pressure the board to spin off the high-growth, direct-to-consumer digital business from the legacy physical retail footprint. This corporate restructuring would unlock sum-of-the-parts value, allowing the market to assign a higher growth multiple to the digital entity.

Key frictions and downside risks

Debt Covenant Breach and Liquidity Crisis

Capital Allocation

25% probabilityStock price impact: -45.0%Earnings impact: Not quantified

A severe consumer spending contraction combined with persistent supply chain cost inflation could compress operating cash flows rapidly. Given the company's high leverage, a sudden drop in EBITDA could trigger technical debt covenant breaches, forcing highly dilutive equity raises or a painful debt restructuring.

Severe Supply Chain Severance

Political And Geopolitical

15% probabilityStock price impact: -40.0%Earnings impact: Not quantified

An escalation in geopolitical conflicts or a dramatic expansion of trade tariffs could completely sever access to primary manufacturing hubs in Asia. Lacking near-term alternative sourcing, the company would face catastrophic inventory stock-outs ahead of critical holiday seasons, leading to permanent market share loss.

W:NYSEHQ:Listed:

Consumer Discretionary Β· Homefurnishing Retail

Online furniture and home goods retailer offering millions of products through direct-to-consumer e-commerce platform.

RatingSell All

Latest editorial review

Reviewed through 24 Aug 2026

Based on deep-analysis report: 5 Jul 2026 Β· newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

The editor's view

The original investment case and current rating remain supported as of 2026-08-24T15:12:25Z. Stronger free cash flow is meaningful counter-evidence, but one quarter does not yet overturn the dual-horizon caution around demand and durable profitability. Monitor the next material filing, policy decision, protocol release, or operating update.

What to watch

The main risk to the avoid view is a durable improvement in cash generation, funding needs, and execution that persists beyond one quarter. Watch for several reporting periods of durable cash-flow, funding, and execution improvement that could disprove the avoid case.

-39.1%
Model rating: Partially Sell
β€”Dividend yield (net)
β€”Buyback yield
Unavailable
25/100
24/100

Flagship insight

Why Rising Maritime Freight Rates Threaten to Unravel the E-Commerce Turnaround Narrative

There is high consensus across reports that a structural housing freeze and soaring transpacific freight rates present severe headwinds. While cost-cutting temporarily boosted free cash flow, the underlying negative equity and expensive debt refinancing create a fragile operational setup, threatening significant valuation compression as margin pressures intensify.

The company is currently seen as a successful turnaround story because of recent cost-cutting and positive cash flow. However, this positive view ignores major problems in the housing market and global shipping. High mortgage rates make it hard for people to move, which directly reduces the demand for new furniture. At the same time, global shipping conflicts are driving up the cost of importing large items, which will squeeze profits. The company's heavy debt load and negative net worth make it highly vulnerable to these challenges, meaning the current recovery may be short-lived.

  • High mortgage rates keep the housing market frozen, reducing the need for new home furniture.
  • Rising ocean shipping costs make importing bulky furniture much more expensive, hurting profit margins.
  • Swapping cheap debt for expensive secured debt increases interest payments and drains available cash.
  • A deeply negative net worth means there is no financial cushion if business conditions worsen.
  • Using artificial intelligence helps cut some office costs but cannot fix expensive physical shipping problems.
  • Intense competition from giant retailers like Amazon limits the company's ability to raise prices.

Advisor consensus

Overall, advisors show high price-direction agreement with limited disagreement. Read on to see where advisor views still differ.

The primary disagreement across reports centers on the long-term valuation of the proprietary logistics network and the timing of a housing recovery. Optimistic views assume that the logistics infrastructure can successfully transition into a high-margin third-party platform, justifying the current valuation. Conversely, more cautious perspectives argue that this infrastructure is a capital-heavy burden that fails to create a durable moat. Additionally, reports diverge on the risk weighting of the 2027 tariff cliff, with some treating the delay as a permanent reprieve and others viewing it as an impending terminal margin tax.

Risk and opportunity map

What could improve the case

Rapid Mortgage Rate Collapse

Macroeconomic And Macrofinancial

25% probabilityStock price impact: +40.0%Earnings impact: Not quantified

A severe economic downturn could force the central bank into aggressive rate cuts, driving mortgage yields below 5%. This would rapidly unfreeze the housing market, triggering a massive wave of home relocations and a subsequent furniture buying frenzy, supercharging top-line growth.

Strategic Acquisition Buyout

Competitive Positioning

15% probabilityStock price impact: +35.0%Earnings impact: Not quantified

A well-capitalized retail giant seeking to match competitors in the bulky-goods category could acquire the company to absorb its CastleGate logistics infrastructure and supplier database. A buyout would resolve balance-sheet toxicity and trigger an immediate premium for equity holders.

Key frictions and downside risks

Debt Covenant Breach and Liquidity Crisis

Capital Allocation

35% probabilityStock price impact: -60.0%Earnings impact: Not quantified

The combination of surging freight costs and doubled interest expense could drive free cash flow deep into negative territory, breaching leverage covenants on secured notes. This would trigger a severe liquidity crisis, forcing highly dilutive equity issuance or distressed restructuring.

Sino-US Trade Architecture Rupture

Political And Geopolitical

20% probabilityStock price impact: -50.0%Earnings impact: Not quantified

An escalation in global trade friction leading to broad systemic embargoes or extreme tariffs on Chinese imports would sever the company's low-cost inventory pipeline. Near-shoring bulky manufacturing is prohibitively expensive and slow, guaranteeing a catastrophic collapse in revenue.

The leading five

The Top 5

#5 β†’ #1

Five ideas remain. Each passed the full editorial review and earned a place in this edition's highest-conviction group.

BBAI:NYSEHQ:Listed:

Information Technology Β· Internet Services & Infrastructure

Artificial intelligence and machine learning company providing decision intelligence solutions for defense and commercial markets.

RatingSell All

Latest editorial review

Reviewed through 24 Aug 2026

Based on deep-analysis report: 5 Jul 2026 Β· newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

The editor's view

The original investment case and current rating remain supported as of 2026-08-24T15:12:25Z. The quarter adds current operating evidence but does not yet disprove the avoid thesis around losses, financing, and contract execution. Monitor the next material filing, policy decision, protocol release, or operating update.

What to watch

The main risk to the avoid view is a durable improvement in cash generation, funding needs, and execution that persists beyond one quarter. Watch for several reporting periods of durable cash-flow, funding, and execution improvement that could disprove the avoid case.

-41.8%
Model rating: Partially Sell
β€”Dividend yield (net)
β€”Buyback yield
Unavailable
40/100
2/100

Flagship insight

Why This Speculative Defense Technology Asset Faces Severe Valuation Multiple Compression

A sharp divergence exists regarding this defense technology asset. While some highlight its fortified balance sheet and sovereign AI integration potential, the overarching consensus warns of extreme valuation multiples colliding with contracting organic revenues. Structural dilution remains the primary risk, while federal procurement tailwinds serve as the main driver.

This company is currently caught in a major gap between its popular stock market story and its actual financial health. Regular investors often view it as a fast-growing artificial intelligence business, but its actual financial results show a shrinking consulting business that is losing money. While the company recently cleared its debt by issuing a massive number of new shares, this move has heavily diluted existing shareholders. Over the long term, the stock is highly likely to experience a major price drop as the market begins to judge the company on its actual profits rather than its buzzwords.

  • The stock is priced at an extremely high multiple of its sales, which is unsustainable.
  • Massive creation of new shares has permanently reduced the value of each individual share.
  • The company is actually shrinking its revenue even during a massive industry boom.
  • High interest rates make it very difficult and expensive for unprofitable companies to survive.
  • New, larger artificial intelligence companies coming to the stock market will draw investor money away.
  • Government contracts are slow to pay out and highly unpredictable, causing volatile earnings.

Advisor consensus

Overall, advisors show very high price-direction agreement and low disagreement. Read on to see where advisor views still differ.

The primary disagreement across the reports centers on the company's valuation horizon and the viability of its platform transition. Bullish perspectives focus on the near-term elimination of debt and the expansion of gross margins following recent software acquisitions, arguing these moves buy the company a multi-year runway to scale. Conversely, bearish analyses emphasize the immediate, devastating impact of share dilution and organic revenue contraction, asserting that the business remains a structurally unprofitable consulting firm whose extreme multiple must compress rapidly regardless of its cash buffer.

Risk and opportunity map

What could improve the case

Strategic Defense Prime Acquisition

Competitive Positioning

25% probabilityStock price impact: +45.0%Earnings impact: Not quantified

A major defense prime seeking to quickly acquire cleared personnel, federal contract vehicles, and biometric capabilities buys the company at a premium. This buyout scenario becomes highly probable if the valuation compresses to realistic levels, offering a sudden exit for trapped capital. While this represents a terminal event rather than organic growth, the potential for a strategic acquisition provides a speculative floor for the stock price during severe market downturns.

Transformational Sole-Source Contract

Sector And Industry

15% probabilityStock price impact: +50.0%Earnings impact: Not quantified

The company successfully secures a massive, multi-year sole-source enterprise artificial intelligence mandate from the Department of Defense. This surprise award would instantly validate the company's technology, reverse the organic revenue contraction, and trigger a massive short squeeze among bearish traders. Such a contract would provide long-term revenue visibility and immediately pull forward the timeline to profitability, fundamentally altering the investment thesis.

Key frictions and downside risks

Liquidity Crisis and Restructuring

Macroeconomic And Macrofinancial

40% probabilityStock price impact: -80.0%Earnings impact: Not quantified

Continued negative free cash flow rapidly depletes the company's cash buffer. If capital markets freeze or refuse further equity dilution under tight monetary conditions, the company faces an acute solvency crisis. This would force a distressed restructuring or bankruptcy filing that completely wipes out common equity holders, as creditors demand draconian terms to keep the business running, resulting in total capital loss.

Reverse Split and Delisting Cycle

Capital Allocation

35% probabilityStock price impact: -50.0%Earnings impact: Not quantified

Severe multiple compression drags the stock price below the minimum listing requirements of the exchange. Management is forced to execute a reverse stock split to maintain compliance, triggering institutional abandonment, passive index exclusion, and a self-reinforcing downward spiral. This technical capitulation would destroy remaining retail confidence, leaving the stock highly vulnerable to aggressive short-selling and permanent value impairment.

AEHR:NASDAQHQ:Listed:

Information Technology Β· Semiconductor Materials & Equipment

Semiconductor test equipment company supplying wafer-level burn-in and test systems for silicon carbide, sensors, and photonics.

RatingSell All

Latest editorial review

Reviewed through 24 Aug 2026

Based on deep-analysis report: 5 Jul 2026 Β· newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

The editor's view

The original investment case and current rating remain supported as of 2026-08-24T15:12:25Z. Record bookings are counter-evidence, but they do not yet resolve customer concentration, revenue volatility, and execution risk across both horizons. Monitor the next material filing, policy decision, protocol release, or operating update.

What to watch

The main risk to the avoid view is a durable improvement in cash generation, funding needs, and execution that persists beyond one quarter. Watch for several reporting periods of durable cash-flow, funding, and execution improvement that could disprove the avoid case.

-48.2%
Model rating: Partially Sell
β€”Dividend yield (net)
β€”Buyback yield
Unavailable
50/100
9/100

Flagship insight

Why This Overvalued Semiconductor Testing Pioneer Faces A Severe Valuation Reset

There is high consensus that the asset faces severe near-term multiple compression despite its strategic pivot into silicon photonics. While wafer-level burn-in remains structurally necessary for advanced packaging, extreme customer concentration and cyclical capital equipment digestion present significant headwinds, overshadowing the robust, debt-free balance sheet strength.

This company makes specialized testing equipment for advanced computer chips. While its technology is highly important for the growing artificial intelligence and electric vehicle markets, the stock price has become far too expensive. The company's sales are highly unpredictable because they rely on a few large customers who buy equipment in bursts rather than steady streams, which could lead to a major drop in the stock price when buying slows down.

  • The shift to testing artificial intelligence chips provides a strong new growth path but will take time to show steady profits.
  • Relying on just a few massive customers makes the company's sales highly unstable and risky if one customer leaves.
  • A very strong balance sheet with zero debt ensures the company can survive downturns without going bankrupt.
  • Recent drops in electric vehicle demand have hurt current sales, showing how sensitive the business is to market cycles.
  • High interest rates across the economy make expensive stocks less attractive to investors, creating a tough market environment.
  • Future success depends on selling replaceable testing parts, which provide more stable and profitable revenue over time.

Advisor consensus

Overall, advisors show high price-direction agreement with limited disagreement. Read on to see where advisor views still differ.

The primary disagreement across the reports centers on the timing and velocity of the silicon photonics revenue ramp. Some perspectives assume that the massive near-term bookings backlog will drive an immediate, explosive financial recovery that temporarily supports the elevated valuation. Conversely, other assessments argue that execution friction, customer concentration, and long qualification lead times will delay revenue recognition, leaving the company highly vulnerable to immediate multiple compression. There is also minor divergence regarding whether the pristine balance sheet can fully insulate the stock price from macroeconomic headwinds.

Risk and opportunity map

What could improve the case

High-Bandwidth Memory Market Penetration

Innovation And Product

35% probabilityStock price impact: +55.0%Earnings impact: Not quantified

The company could successfully adapt its wafer-level parallel testing systems to penetrate the rapidly scaling High-Bandwidth Memory market. If adopted by major memory manufacturers, this would exponentially expand the total addressable market, diversify the customer base, and establish a highly lucrative, recurring revenue stream.

Strategic Acquisition by Industry Leader

Competitive Positioning

20% probabilityStock price impact: +40.0%Earnings impact: Not quantified

A larger automated test equipment conglomerate could acquire the company to vertically integrate its proprietary thermal and wafer-level contactor patents. This buyout would instantly eliminate competitive threats and deliver an immediate, substantial premium to shareholders, bypassing the challenges of the standalone cyclical hardware model.

Key frictions and downside risks

AI Infrastructure Capex Freeze

Sector And Industry

40% probabilityStock price impact: -60.0%Earnings impact: Not quantified

If hyperscalers fail to monetize generative AI, growing scrutiny over return on investment could trigger a sudden, industry-wide freeze in data center capital expenditures. This would evaporate the company's newly formed silicon photonics bookings backlog, leaving it with stranded inventory and a severely impaired growth narrative.

Incumbent Technological Encroachment

Competitive Positioning

30% probabilityStock price impact: -50.0%Earnings impact: Not quantified

Well-capitalized automated test equipment giants could successfully engineer around the company's thermal management patents to launch competing high-capacity wafer-level burn-in systems. This would destroy the company's niche monopoly, trigger a destructive price war, and permanently impair its long-term gross margins and market share.

The finalists

The Top 3

#3 β†’ #1

The shortlist is over. These three stocks earned the strongest conviction in this edition. Count down to the research team's number-one pick.

Checking your access...

The winner

The Number-One Pick

The edition's highest-conviction selection, combining near-term opportunity with long-term confirmation.

Edition ranking

Top 10 sell signals out of 376 deeply analyzed assets

Compare only the ranked assets presented in this edition. The table never extends beyond the visible editorial list.

Table Definitions

Definitions for every metric available in the Top Picks table.

Note: To sort the table, click the header of the column you want to sort.

Editorial Category Rank
The selected asset’s position within this edition’s editorial category. This human-reviewed selection order is independent of its quantitative universe rank.
Asset Universe Rank
The asset’s quantitative rank within the analyzed asset universe for the selected scoring snapshot. Original published ranks are preserved when an editorial table shows only a subset of assets.
Asset Name
The ranked asset in this Top Picks view, including name, ticker, market category, and listing context where available.
Price Data Cutoff Date
The market price date used for this row. Recomputed ranking snapshots can use newer closes than the original deep-analysis batch.
Cross-Horizon Score
A governed 0-100 candidate score that combines the remaining one-year outlook with confirmed five-year direction, confidence, financial health, and risk. It supports editorial review and does not replace either horizon rating.
iPulse Score
iPulse AI Consensus Score combines expected return, risk-adjusted return, advisor agreement, and risk-pressure inputs into one ranked signal.
Consensus Rating
Consensus Rating is the plain-language buy, hold, or sell interpretation of the iPulse AI consensus score for the selected horizon.
Expected Return Including Dividends
Total compounded expected return over the full selected horizon, including reinvested annual net dividends when applicable.
Annualized Return
Annualized expected return expressed as a one-year-equivalent rate for the selected forecast horizon.
Net Dividend Contribution
Annualized net dividend contribution used by the scoring pipeline, estimated from historical cash-dividend events after tax assumptions and outlier filtering. When a legacy immutable snapshot omitted the input field, the page derives the contribution only from that snapshot’s frozen dividend-inclusive and price-only return outputs; it never substitutes current dividend data.
P/E Ratio
Trailing P/E ratio. For example, 21.7 means the market value is 21.7x trailing earnings.
Event Risks
The Event Risks column summarizes clustered consensus frictions and tail risks as Very Low (0-19), Low (20-39), Moderate (40-59), High (60-79), or Very High (80-100). The number is a relative pressure score, not a probability of loss or a complete measure of investment risk.
Financial Health
0-100 equity-only financial quality score using liquidity, leverage safety, profitability, cash generation, and operating trend.
Annualized Historic Volatility
Annualized historical price volatility from daily returns, used as a risk denominator in scoring.
Direction Agreement
Percentage of advisors whose predicted direction matches the consensus direction.
Grouped Voices
Vote-count summary across raw voices, distinct advisors, personas, models, and adjusted grouped votes.
Advisors
Number of distinct advisor identities contributing forecasts for this asset in the selected batch, mode, and horizon.
Forecast Price / Initial Price
Projected consensus price at the selected horizon, shown against the initial/latest close price used by the snapshot.
Detailed Methodology
Top Picks ranked assets and investment research metrics. Select an asset name or its row to open the asset report.
Editorial Category RankAsset Universe RankAsset NameCross-Horizon ScoreiPulse ScoreConsensus RatingExpected Return Including DividendsEditorial commentAnnualized ReturnNet Dividend ContributionP/E RatioEvent RisksFinancial HealthDirection AgreementGrouped VoicesAdvisorsForecast Price and Initial Price
#4355
AEHR.NASDAQ
Aehr Test Systems (AEHR)
Stocks
Data 47d old
96.9/100
-279
SELL ALL-64.2%The original investment case and current rating remain supported as of 2026-08-24T15:12:25Z. Record bookings are counter-evidence, but they do not yet resolve customer concentration, revenue volatility, and execution risk across both horizons. Monitor the next material filing, policy decision, protocol release, or operating update.-64.2%0.0%β€”Very High (91)5092%128$36.4($101.7)
#536396.6/100
-340
SELL ALL-37.9%The original investment case and current rating remain supported as of 2026-08-24T15:12:25Z. The quarter adds current operating evidence but does not yet disprove the avoid thesis around losses, financing, and contract execution. Monitor the next material filing, policy decision, protocol release, or operating update.-37.9%0.0%β€”Very High (98)4092%128$2.00($3.22)
#6374
W.NYSE
Wayfair Inc (W)
Stocks
Data 47d old
96.6/100
-513
SELL ALL-42.2%The original investment case and current rating remain supported as of 2026-08-24T15:12:25Z. Stronger free cash flow is meaningful counter-evidence, but one quarter does not yet overturn the dual-horizon caution around demand and durable profitability. Monitor the next material filing, policy decision, protocol release, or operating update.-42.2%0.0%β€”High (77)25100%128$58.7($101.5)
#737396.3/100
-481
SELL ALL-41.7%The original investment case and current rating remain supported as of 2026-08-24T15:12:25Z. The scheduled earnings update did not provide completed evidence sufficient to reverse the dual-horizon caution; demand and margin repair remain unproven. Monitor the next material filing, policy decision, protocol release, or operating update.-41.7%0.0%34.4xHigh (71)36100%128$49.8($85.4)
#836896.2/100
-391
SELL ALL-41.0%The original investment case and current rating remain supported as of 2026-08-24T15:12:25Z. The update refreshed technical progress and liquidity, but does not yet resolve commercialization, dilution, and execution risks behind the avoid case. Monitor the next material filing, policy decision, protocol release, or operating update.-41.0%0.0%β€”Very High (97)4692%128$10.57($17.91)
#9370
HIMS.NYSE
Hims Hers Health Inc (HIMS)
Stocks
Data 47d old
95.4/100
-429
SELL ALL-34.9%The original investment case and current rating remain supported as of 2026-08-24T15:12:25Z. The quarter provides current growth evidence, but regulatory, product, and valuation risks remain sufficient to retain the dual-horizon caution. Monitor the next material filing, policy decision, protocol release, or operating update.-34.9%0.0%β€”Very High (85)4792%128$22.0($33.8)
#10360
SOUN.NASDAQ
SoundHound AI Inc (SOUN)
Stocks
Data 47d old
94.0/100
-302
SELL ALL-40.4%The original investment case and current rating remain supported as of 2026-08-24T15:12:25Z. Record revenue and higher outlook are counter-evidence, but do not yet resolve valuation, cash-flow, concentration, and execution risk across both horizons. Monitor the next material filing, policy decision, protocol release, or operating update.-40.4%0.0%β€”Very High (94)5475%128$4.36($7.32)

Market context and selection approach

Some companies reported better bookings, revenue, or cash flow, but persistent losses, funding needs, dilution, valuation, demand weakness, or execution risk remain unresolved.

Every selection passes the strict dual-horizon Sell gate. Positive updates are treated as counter-evidence, and the avoid view changes only after durable operating and funding repair.

References

Frozen links are separated into editorial-review evidence, 5–6 global-context references, and 3–4 governed Researcher citations per selected asset. Duplicate URLs appear once; the combined citation list is capped at 30.

B. Global market context

These dated files capture broader market, macroeconomic, policy, and cross-asset context. Each frozen file is supplied as input to every advisor model during deep analysis; its citations never count toward an asset-specific minimum.

  1. 5.Federal Reservehttps://www.federalreserve.gov/monetarypolicy/fomccalendars.htm
  2. 6.US Bureau of Labor Statisticshttps://www.bls.gov/cpi/data.htm
  3. 7.US Bureau of Economic Analysishttps://www.bea.gov/data/gdp/gross-domestic-product
  4. 8.US Treasuryhttps://home.treasury.gov/resource-center/data-chart-center/interest-rates
  5. 9.US Energy Information Administrationhttps://www.eia.gov/
  6. 10.Reuters Worldhttps://www.reuters.com/world

C. Asset-specific deep-analysis sources

Captured by governed AI Researcher agents. Shared URLs are shown once and identify every selected asset they support.

Asset-specific Researcher citations remain available in each linked deep analysis above; this original edition did not add a second citation set.

Important information

Research scope and investor notice

Research scope

  • External evidence was limited to material current-event validation through the frozen cutoff; the underlying complete-batch analysis was not rerun.
  • Forecasts, ratings, ranks, returns, financial-health values, and risk values remain frozen and may not capture later events.
  • The named human editor reviewed the evidence and approved this edition for publication. Readers should inspect the cited sources and apply independent judgment.

Investor notice

AI-assisted editorial research for informational and educational purposes. This edition was reviewed and approved by a named human editor. It is not personalized investment advice or a promise of future performance.

Forecasts, ratings, and return estimates are uncertain and may change as new evidence becomes available.