Assets

iPulse AI Editorial Picks research

Best Energy Stocks

Explore the best energy stocks across the governed oil-and-gas, refining, pipeline, power-generation, renewable-energy, and energy-equipment and services universe. iPulse AI combines one-year return potential with five-year trend confirmation, multi-agent consensus, business quality, financial health, valuation, and risk resilience. The review also tests commodity-price exposure, project economics, capital discipline, regulation, energy-transition risk, and cash-flow durability. Every selection includes a clear thesis, projected returns, catalysts, and the risks that could change the outlook.

Explore overall iPulse AI portfolio strategies and performance

Editorial ApproverRusslan Ramdowar iPulse AI Engine V7 15 min read
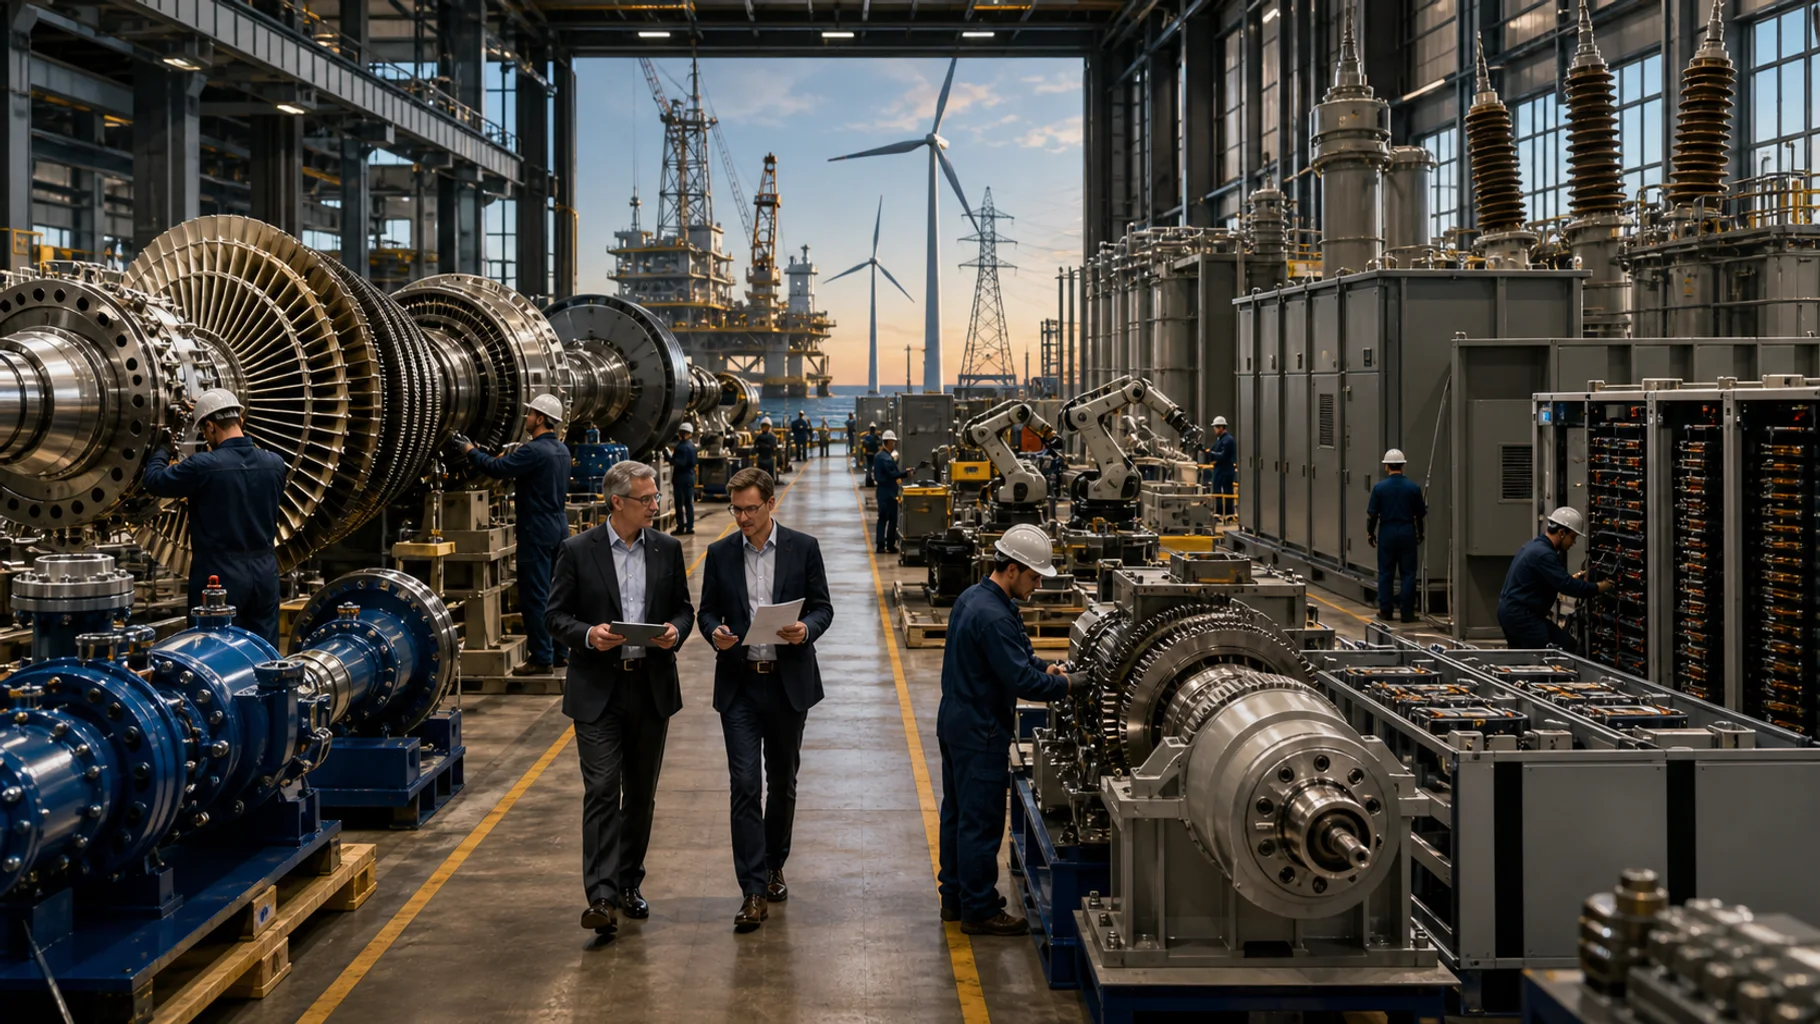
Engineers maintain turbines, subsea equipment, transformers, switchgear, renewable components, batteries, and service robotics while investors assess durable energy-equipment businesses.

Our Approach: The broad screening universe covers about 100,000 stocks; it is not the number of assets with published forecasts. For this edition, 426 assets passed preselection and underwent deep multi-agent analysis. iPulse AI Engine V7 ranked the top 10, and 10 Editorial Top Picks passed the separate evidence review and approval workflow. Read the detailed methodology

Editorial Picks countdown

Top 10 Editorial Picks

TTE:PARHQ:Listed:

Energy ยท Integrated Oil & Gas

French multinational integrated energy company engaged in oil and gas production, refining, and renewable energy development worldwide.

RatingBuy

Latest editorial review

Reviewed through 5 Oct 2026

Based on deep-analysis report: 20 Sept 2026 ยท newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

low-cost production and integrated gas operations support cash returns while new power investments broaden the earnings base.

What to watch

The next results for capital spending discipline and whether power investments generate cash as commodity prices normalize.

+76.9%
Excl. dividends: +43.1%
4.3%Dividend yield (net)
โ€”Buyback yield
10.6x
Price as of: 2026-10-02
40/100
78/100

Flagship insight

Integrated Energy Fortress Balances Windfall Cash With Long Term Transformation

A high consensus confirms robust near-term cash generation underpinned by sub-thirty-dollar upstream breakevens and aggressive share retirements. Sharp divergence centers on whether post-2027 global LNG capacity additions and renewable power capital dilution will compress returns as geopolitical supply premia normalize across Europe.

TotalEnergies is a major global energy company producing oil, natural gas, and electricity at some of the lowest costs in the industry. Because it can produce oil profitably even if prices fall to thirty dollars per barrel, it generates immense cash during periods of high energy prices. Management uses this excess cash to pay growing dividends and buy back its own shares, steadily increasing each remaining shareholder's piece of the business. While lower future energy prices and European green regulations could limit price surges, the company's strong balance sheet provides reliable income and stability.

  • Ultra-low production costs protect profits and ensure dividend payments even during major global oil price downturns.
  • Continuous share repurchases reduce total share count, boosting per-share earnings and dividend coverage year after year.
  • Global natural gas contracts and power generation create dependable cash streams that balance out volatile crude oil swings.

Advisor consensus

Overall, advisors show very high price-direction agreement and low disagreement. Read on to see where advisor views still differ.

The decisive analytical tension centers on the normalization path of energy earnings and the true capital efficiency of Integrated Power. Optimistic views argue that structural Middle Eastern supply friction and deepwater volume additions will keep free cash flow yields above eight percent, justifying multiple re-rating. Skeptical views counter that peak 2026 cash flows embed roughly nine billion dollars of unrepeatable war premium, warning that the post-2027 global LNG capacity surge and single-digit power returns will erode return on capital. The debate hinges on observing whether Integrated Power achieves positive free cash flow without external equity dilution by 2028.

Risk and opportunity map

Longer-term opportunities

Primary United States Listing Execution

Capital Allocation

32% probabilityStock price impact: +24.0%Earnings impact: Not quantified

A successful migration of the primary listing or dual-listing structure to the New York Stock Exchange would dismantle the structural European ESG valuation discount. Accessing deep US institutional energy capital would re-rate trading multiples toward American peer levels. French political opposition keeps likelihood below fifty percent, but realization would prompt immediate multiple re-rating.

Namibian Venus Fast-Track Commercialization

Competitive Positioning

36% probabilityStock price impact: +22.0%Earnings impact: Not quantified

Expediting commercial development of the colossal Venus and Mangetti ultra-deepwater discoveries offshore Namibia would unlock hundreds of thousands of ultra-low-cost barrels daily ahead of schedule. Technical subsea complexity keeps probability below half, but commercial sanctioning would substantially expand high-margin reserve life and prospective free cash flow generation.

Tail risks

Synchronized Global Recession Demand Collapse

Macroeconomic And Macrofinancial

28% probabilityStock price impact: -28.0%Earnings impact: Not quantified

A severe global economic contraction triggered by prolonged central bank tightening could crush physical petroleum consumption, driving Brent crude sustainably below fifty-five dollars. Simultaneous collapse in industrial gas and refining margins would squeeze operating cash flow below fifteen billion dollars, forcing management to eliminate discretionary buybacks and freeze dividends.

Mozambique LNG Security Relapse Rupture

Political And Geopolitical

24% probabilityStock price impact: -19.0%Earnings impact: Not quantified

A sudden resurgence of militant insurgency in Cabo Delgado breaching project perimeters would trigger a renewed indefinite force majeure on the twenty-billion-dollar Mozambique LNG facility. Sunk capital write-downs and deferred multi-decade liquefaction cash flows would impair balance sheet book value and weaken long-term production growth assumptions.
#9BP logoBP
BP:LSEHQ:Listed:

Energy ยท Integrated Oil & Gas

British multinational oil and gas company investing heavily in renewable energy and low-carbon electricity solutions.

RatingBuy

Latest editorial review

Reviewed through 5 Oct 2026

Based on deep-analysis report: 20 Sept 2026 ยท newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

a diversified energy business can generate cash while capital discipline supports distributions through commodity cycles.

What to watch

Lower oil prices or costly project delays could undermine debt reduction and shareholder returns.

+83.9%
Excl. dividends: +42.8%
5.2%Dividend yield (net)
โ€”Buyback yield
21.4x
Price as of: 2026-10-02
39/100
61/100

Flagship insight

Upstream Capital Reallocation Powers Balance Sheet Repair and Eventual Multiple Rerating

A high consensus confirms that structural balance-sheet repair, curtailed low-return transition capital, and high-margin upstream reallocation drive intrinsic equity growth. The primary risk centers on mid-cycle crude normalization eroding operating windfalls before debt reduction targets and buybacks fully materialize.

This investment case turns on a major corporate reset: halting unprofitable clean-energy spending to focus strictly on high-margin oil and gas. Management is using robust energy earnings and asset sales to pay down heavy debt rather than repurchasing shares immediately. Once debt hits safe targets, surplus cash flow will shift back to share buybacks and dividends, narrowing the company's valuation discount against international competitors.

  • Selling peripheral business units reduces borrowing burdens quickly but leaves future profits more vulnerable to oil price swings.
  • Paying off high-interest hybrid debt removes expensive corporate IOUs, leaving more cash available for ordinary shareholders over time.
  • Cutting corporate overhead permanently protects baseline dividend payments even if global crude prices fall back toward seventy dollars.

Advisor consensus

Overall, advisors show very high price-direction agreement and low disagreement. Read on to see where advisor views still differ.

The primary analytical disagreement across reports involves the durability of current cash generation and the appropriate multiple applied to an asset undergoing strategic retrenchment. Bullish perspectives argue that pivoting to low-breakeven hydrocarbons generates an unassailable double-digit free cash flow yield that will mechanically force multiple re-rating toward international peer averages as debt targets are met. Conversely, skeptical frameworks contend that current profitability is almost entirely a rented geopolitical windfall masking asset shrinkage, highlighting that divesting crown jewels like Castrol permanently reduces earnings quality. Resolving this tension requires observing whether structural operating costs fall in real terms while net debt enters the target band during commodity price pullbacks.

Risk and opportunity map

Longer-term opportunities

Surplus distribution framework and buyback restoration

Capital Allocation

36% probabilityStock price impact: +28.0%Earnings impact: Not quantified

Accelerated divestment execution and sustained crude realizations push net debt below the fourteen-billion-dollar threshold by late 2027, ahead of schedule. Management responds by reinstating an aggressive, rule-based capital return framework targeting over five billion dollars in annual repurchases alongside special dividends. This rapid equity float retirement forces institutional re-weighting and accelerates multiple convergence.

Primary equity listing relocation to America

Capital Allocation

24% probabilityStock price impact: +36.0%Earnings impact: Not quantified

Activist pressure spearheaded by major institutional investors forces the board to approve a primary listing transfer or corporate redomiciliation to the New York Stock Exchange by 2028. Escaping the structural London conglomerate discount instantly grants access to deep US index capital, eliminating the thirty percent valuation gap against domestic integrated peers.

Tail risks

Synchronized global recession crushes petroleum consumption

Macroeconomic And Macrofinancial

28% probabilityStock price impact: -32.0%Earnings impact: Not quantified

Cumulative monetary tightening triggers an abrupt global industrial recession by late 2027, coinciding with diplomatic conflict resolution that reopens blocked export routes. Brent crude plummets below fifty-five dollars per barrel while refining cracks collapse. Squeezed operating cash flows fail to cover capital budgets, forcing extended buyback suspensions and defensive dividend reductions.

Catastrophic deepwater operational containment disaster

Operational Efficiency

13% probabilityStock price impact: -40.0%Earnings impact: Not quantified

A severe well-control failure or catastrophic subsea pipeline rupture occurs across core deepwater assets in the Gulf of Mexico or Brazilian pre-salt. Echoing historical environmental crises, the disaster triggers emergency drilling moratoria, severe statutory fines, and multi-billion-dollar uncapped litigation liabilities, wiping out free cash flow and destroying institutional governance confidence.

#8BYD logoBYD
1211:HKEXHQ:Listed:

Consumer Discretionary ยท Automobile Manufacturers

Chinese multinational conglomerate specializing in electric vehicles, batteries, and renewable energy, competing with Tesla in EV market.

RatingBuy

Latest editorial review

Reviewed through 5 Oct 2026

Based on deep-analysis report: 20 Sept 2026 ยท newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

integrated batteries and vehicle production offer cost advantages as exports broaden the demand base.

What to watch

Overseas tariffs or domestic price competition could reduce margins despite rising vehicle shipments.

+97.3%
Excl. dividends: +89.7%
0.8%Dividend yield (net)
โ€”Buyback yield
20.9x
Price as of: 2026-10-02
32/100
35/100

Flagship insight

Global Production Expansion Overcomes Domestic Price Pressures and Capital Constraints

High consensus among synthesized reports confirms that international factory localization in Hungary and Brazil will neutralize punitive export tariffs. While brutal domestic price wars compressed operating margins, expanding overseas deliveries carrying superior unit profits anchor a multi-year recovery in free cash flow and earnings.

The company is shifting from relying on China's crowded car market toward selling higher-priced electric and hybrid vehicles globally. While a vicious price war in China hurt recent profit margins and expensive factory construction drained cash, international sales have surged to over half of total revenue. As newly built factories in Europe and South America begin production, they will bypass expensive import taxes and turn strong sales into real cash earnings.

  • Making batteries, computer chips, and parts in-house gives the company an unbeatable manufacturing cost advantage.
  • Local production in Europe will dodge heavy 27% import taxes, directly boosting profit per vehicle.
  • As multi-year factory construction finishes, heavy spending will decline, leaving far more cash for shareholders.

Advisor consensus

Overall, advisors show very high price-direction agreement and low disagreement. Read on to see where advisor views still differ.

The primary analytical disagreement across reports involves whether negative free cash flow reflects structural capital destruction or a disciplined, front-loaded capacity investment. Conservative perspectives argue that extreme capital intensity, rising depreciation, and reliance on supplier payables leave the balance sheet vulnerable to domestic price deflation. Optimistic views counter that auto-segment gross margins of 22.33% and surging exports prove that the profit pool is already decoupling from China. This debate will be resolved by monitoring whether rolling free cash flow turns sustainably positive as the Hungarian facility enters series production.

Risk and opportunity map

Longer-term opportunities

European minimum price undertaking accord

Regulatory

30% probabilityStock price impact: +32.0%Earnings impact: Not quantified

Bilateral diplomatic negotiations between Brussels and Beijing establish a minimum import price undertaking that replaces countervailing duties with localized manufacturing quotas. This agreement unlocks unpenalized European distribution for Hungarian production, expanding regional operating margins toward 10% and driving a swift equity re-rating. Protectionist industrial pressures keep probability below 35%.

Commercial solid state battery deployment

Innovation And Product

26% probabilityStock price impact: +38.0%Earnings impact: Not quantified

Accelerated commercialization of an all-solid-state Blade battery cell by late 2028 doubles volumetric energy density while eliminating thermal runaway risks. Achieving high-yield production ahead of global rivals creates an unassailable technology moat, unlocking lucrative third-party licensing royalties and expanding vehicle gross margins by 400 basis points.

Tail risks

Coordinated Western connected vehicle ban

Regulatory

28% probabilityStock price impact: -36.0%Earnings impact: Not quantified

Western regulatory authorities enact sweeping national-security prohibitions against Chinese connected-vehicle software, telematics, and sensor hardware by 2027. Such an embargo would paralyze European and Indo-Pacific export channels, stranding multi-billion-dollar localized factory investments in Hungary and triggering severe asset write-downs. Complex geopolitical negotiations keep probability at 28%.

Supplier credit working capital crisis

Operational Efficiency

24% probabilityStock price impact: -30.0%Earnings impact: Not quantified

A synchronized regulatory compression of Chinese automaker supplier payment tenors collides with ongoing negative free cash flow, creating an acute liquidity strain. If working-capital payables unwind rapidly while capital expenditures remain elevated, management would be forced into dilutive equity issuance or high-cost borrowing. Robust state banking ties keep probability at 24%.

0883:HKEXHQ:Listed:

Energy ยท Oil & Gas Exploration & Production

Chinese offshore oil and gas producer focused on exploration, development, and production assets in China and international basins.

RatingBuy

Latest editorial review

Reviewed through 5 Oct 2026

Based on deep-analysis report: 20 Sept 2026 ยท newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

low-cost offshore production supports cash generation while reserve development extends the resource base.

What to watch

Energy price declines or geopolitical restrictions could weaken cash available for investment and dividends.

+106.0%
Excl. dividends: +38.8%
8.2%Dividend yield (net)
โ€”Buyback yield
3.8x
Price as of: 2026-10-02
71/100
60/100

Flagship insight

Offshore Cost Moat Drives Compelling Long-Term Upstream Cash Distributions

A dense synthesis reveals high consensus on upstream unit cost leadership below thirty dollars per barrel and fortress net-cash liquidity. However, a sharp divergence separates expectations of valuation multiple expansion from risks of post-war crude normalization, windfall levies, and geopolitical investment restrictions.

This offshore energy producer functions like a low-cost cash machine. Because it extracts oil and natural gas for under thirty dollars a barrel, it remains highly profitable even when global commodity prices drop. Management uses this financial strength to maintain a debt-free balance sheet and pay generous cash dividends. While falling oil prices and investment limits prevent runaway stock gains, reliable production growth and large dividend checks provide dependable, defensive value for patient shareholders.

  • World-class extraction costs ensure strong profits and cash generation even during severe oil price downturns.
  • Expanding deepwater projects in South America provide growing production away from vulnerable maritime transit chokepoints.
  • Reliable forty-five percent dividend payouts deliver attractive cash income that cushions against general market volatility.

Advisor consensus

Overall, advisors show very high price-direction agreement and low disagreement. Read on to see where advisor views still differ.

The decisive disagreement centers on terminal multiple expansion versus dividend-only total return. One perspective argues that Southbound Stock Connect liquidity will aggressively eliminate the sovereign discount, driving price-to-earnings multiples from seven toward Western peer levels near ten times. The opposing perspective contends that progressive windfall levies, OFAC investment restrictions, and Chinese transport electrification enforce an enduring valuation ceiling, meaning returns will derive almost entirely from cash dividends as crude normalizes toward seventy-five dollars. Auditing upcoming dividend coverage ratios and Southbound ownership percentages will resolve whether multiple re-rating or yield harvesting dominates.

Risk and opportunity map

Longer-term opportunities

Protracted maritime chokepoint transit closure

Political And Geopolitical

25% probabilityStock price impact: +35.0%Earnings impact: Not quantified

Severe military interdiction permanently closing the Strait of Hormuz and damaging alternative Middle Eastern pipelines would trigger an acute global supply deficit, driving Brent crude above one hundred thirty dollars per barrel. Sheltered domestic offshore fields and unhedged Atlantic barrels would capture massive windfall profits, swelling annual free cash flow and triggering extraordinary special dividend distributions.

Frontier deepwater South China mega-discovery

Innovation And Product

28% probabilityStock price impact: +25.0%Earnings impact: Not quantified

Advanced subsea seismic exploration unlocking a commercial discovery exceeding one billion barrels of oil equivalent in deepwater South China Sea basins would radically extend proved reserve life. Fast-track state permitting and tie-ins to coastal pipelines would rapidly expand long-term domestic natural gas production, prompting a major upward institutional reassessment of net asset replacement value.

Tail risks

Synchronized global recession demand collapse

Macroeconomic And Macrofinancial

28% probabilityStock price impact: -32.0%Earnings impact: Not quantified

Aggressive central bank policy tightening combined with compounding trade barriers could precipitate a synchronized worldwide recession, collapsing crude demand and pushing Brent prices below fifty dollars. Substantially reduced revenues would compress upstream margins, halve operating cash flow, and force severe reductions in statutory dividend payouts despite rock-bottom extraction costs.

Secondary sanctions targeting overseas assets

Political And Geopolitical

18% probabilityStock price impact: -38.0%Earnings impact: Not quantified

Escalating geopolitical confrontation could lead Western authorities to enact comprehensive secondary sanctions targeting international joint ventures, forcing the freeze or divestment of the twenty-five percent Stabroek working interest in Guyana. Forfeiting this premier deepwater asset would eliminate fifteen percent of forward production growth and trigger massive international asset impairments.

ENGI:PARHQ:Listed:

Utilities ยท Electric Utilities

French multinational electric utility company focusing on renewable energy, natural gas, and energy services. important player in the global energy transition.

RatingStrong Buy

Latest editorial review

Reviewed through 5 Oct 2026

Based on deep-analysis report: 20 Sept 2026 ยท newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

regulated networks and renewable assets provide recurring cash as the business manages its nuclear transition.

What to watch

Unresolved nuclear obligations or delayed asset transfers could constrain investment and shareholder distributions.

+90.6%
Excl. dividends: +39.5%
6.4%Dividend yield (net)
โ€”Buyback yield
9.2x
Price as of: 2026-10-02
26/100
91/100

Flagship insight

European Utility Pivot Anchors Regulated Compounding Despite Transitory Balance Sheet Leverage

There is high consensus that strategic regulated network expansion and nuclear liability ring-fencing permanently upgrade earnings durability. However, sharp divergence persists regarding post-acquisition debt absorption and normalizing merchant energy spreads. Inflation-indexed rate bases and high dividend yields provide solid valuation support across macroeconomic cycles.

This company is transforming from an unpredictable energy trader into a stable infrastructure giant. By purchasing major electric distribution grids and transferring old nuclear plant cleanup liabilities to the government, management is building a predictable, utility-style business. Although taking on debt to fund this makeover creates temporary financial risk, steady cash flows from regulated networks and long-term clean energy contracts protect investor profits and support an attractive, reliable dividend.

  • Electric grid and gas storage monopolies guarantee stable, inflation-protected cash flows regardless of economic downturns.
  • High debt from recent acquisitions requires disciplined debt repayment to maintain healthy corporate credit ratings.
  • An attractive dividend yield pays investors well while the company completes its shift toward green infrastructure.

Advisor consensus

Overall, advisors show very high price-direction agreement and low disagreement. Read on to see where advisor views still differ.

The decisive debate among reports concerns whether recent earnings represent a fleeting commodity windfall or the baseline of a structurally de-risked infrastructure platform. Bearish views argue that negative reported free cash flow, sixty billion euros in economic net debt, and normalizing European wholesale spark spreads will trigger multiple de-rating toward tangible book value. Bullish perspectives counter that integrating UK Power Networks and capping Belgian nuclear provisions converts two-thirds of EBIT into predictable, inflation-linked cash flows. Observation of second-half 2026 organic leverage reduction and early 2027 Ofgem price review parameters will resolve this divergence.

Risk and opportunity map

Longer-term opportunities

Dedicated European AI power grid carve-outs

Competitive Positioning

33% probabilityStock price impact: +21.0%Earnings impact: Not quantified

European directives could establish expedited permitting corridors and guaranteed capacity tariffs for behind-the-meter datacenter energy parks. By deploying multi-gigawatt solar, battery storage, and flexible gas assets under twenty-year indexed contracts, the enterprise would capture substantial infrastructure margins, lifting recurring net income by over one billion euros. Grid bottlenecks keep probability at 33%.

Accelerated European hydrogen backbone funding

Regulatory

27% probabilityStock price impact: +17.0%Earnings impact: Not quantified

The European Union could fast-track cross-border hydrogen corridor subsidies and guarantee regulated asset base returns for retrofitting existing gas transport trunklines. Repurposing midstream pipeline networks with substantial state co-funding would eliminate stranded asset risks and significantly expand regulated infrastructure valuation. Protracted member-state fiscal debates restrict realization probability to 27%.

Tail risks

Confiscatory European utility windfall super-tax

Political And Geopolitical

32% probabilityStock price impact: -23.0%Earnings impact: Not quantified

Severe fiscal deficits could prompt emergency sovereign legislation imposing aggressive retrospective windfall taxes on domestic infrastructure and generation assets. Expropriating over one billion euros in annual operating cash flows would impair balance sheet credit metrics and trigger institutional equity liquidation. Institutional investor resistance keeps the discrete event probability capped at 32%.

Regulatory distribution allowed return cut

Regulatory

24% probabilityStock price impact: -18.0%Earnings impact: Not quantified

Upcoming distribution price control determinations could enforce severe cuts on allowed return on equity and capital expenditure baselines across UK electricity networks. Suppressing regulated returns would undermine acquisition accretion assumptions and potentially trigger goodwill impairments on acquired network assets. Established regulatory precedent and legal appeals processes keep realization probability limited to 24%.

The leading five

The Top 5

#5 โ†’ #1

Five ideas remain. Each passed the full editorial review and earned a place in this edition's highest-conviction group.

FLNC:NASDAQHQ:Listed:

Industrials ยท Electrical Components & Equipment

Energy storage technology company providing grid-scale battery systems, software, and services for utilities and renewable developers.

RatingBuy

Latest editorial review

Reviewed through 5 Oct 2026

Based on deep-analysis report: 20 Sept 2026 ยท newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

a growing storage backlog offers revenue visibility as utilities invest in balancing renewable power.

What to watch

Weak contract execution or cost overruns could turn backlog growth into losses and funding pressure.

+190.0%
Model rating: Buy
โ€”Dividend yield (net)
โ€”Buyback yield
N/M
Price as of: 2026-10-02
29/100
18/100

Flagship insight

Massive Energy Storage Order Backlog Counters Acute Factory Ramp Headwinds

High consensus confirms that severe factory assembly bottlenecks and near-term credit covenant tests created acute valuation distress, while a record multi-billion-dollar backlog and data-center storage demand anchor long-term recovery. Operational stabilization remains the primary catalyst against persistent working-capital and commoditization risks.

Fluence Energy experienced a steep share price decline after factory assembly delays in Houston postponed customer deliveries and triggered short-term financial losses. Despite these growing pains, the company maintains a massive multi-billion-dollar order backlog from utilities and artificial intelligence data centers needing dependable battery power. If new operational management stabilizes factory production and repairs profit margins over the next year, the business can move from burning cash to generating steady earnings.

  • Factory production delays simply pushed revenue into future quarters rather than causing customers to cancel orders.
  • Outsourcing assembly keeps factory building costs low but leaves the business vulnerable to partner execution mistakes.
  • Growing artificial intelligence data center power needs provide an urgent, profitable customer base outside traditional utilities.

Advisor consensus

Overall, advisors show very high price-direction agreement and low disagreement. Read on to see where advisor views still differ.

The decisive disagreement centers on whether recent financial guidance cuts represent temporary factory ramp friction or structural business model impairment. Optimistic views argue that manufacturing snags merely shifted four hundred million dollars of contracted revenue into fiscal 2027, leaving multi-year demand intact. Skeptical perspectives assert that pure-play integrators face terminal margin erosion from vertically integrated rivals like Tesla and CATL, while looming credit covenant tests threaten dilutive recapitalizations. Resolving this debate requires monitoring sequential GAAP gross margins and quarterly operating cash flow conversion over the next two reporting periods.

Risk and opportunity map

Longer-term opportunities

Hyperscaler Microgrid Master Standardization Agreement

Sector And Industry

30% probabilityStock price impact: +60.0%Earnings impact: Not quantified

A leading cloud hyperscaler facing catastrophic transmission interconnect queues could formally standardize Fluence's storage architecture across global artificial intelligence campuses. Materializing as a multi-gigawatt direct supply agreement, this partnership would inject over two billion dollars in high-margin commitments, eliminating customer acquisition friction and accelerating software annual recurring revenue.

Strategic Sponsor Privatization Buyout Offer

Management And Governance

22% probabilityStock price impact: +50.0%Earnings impact: Not quantified

Controlling corporate sponsors Siemens or AES could capitalize on depressed public valuations by launching a tender offer to acquire the remaining public float. Driven by the strategic necessity of grid-balancing infrastructure, taking the enterprise private would eliminate compliance overhead and crystallize an immediate control premium for public shareholders.

Tail risks

Lender Covenant Default and Recapitalization

Capital Allocation

26% probabilityStock price impact: -50.0%Earnings impact: Not quantified

Commercial lenders could refuse covenant accommodations following persistent EBITDA deficits, declaring a technical default that restricts revolving credit facilities and letters of credit. Unable to finance project work-in-progress, management would face a distressed, highly dilutive emergency equity offering that permanently impairs existing common shareholder equity value.

Protracted Manufacturing Failure and Backlog Cancellations

Operational Efficiency

22% probabilityStock price impact: -45.0%Earnings impact: Not quantified

If automated tooling and contractor defects at domestic assembly plants remain unresolved through fiscal 2027, major utility customers could invoke contractual cancellation clauses. The resulting customer defections to competing integrated suppliers would destroy backlog visibility, trigger massive liquidated damages, and permanently compromise the core hardware integration franchise.

RELIANCE:NSEHQ:Listed:

Energy ยท Oil & Gas Refining & Marketing

Large Indian private sector company with businesses in energy, petrochemicals, textiles, retail, and telecommunications.

RatingStrong Buy

Latest editorial review

Reviewed through 5 Oct 2026

Based on deep-analysis report: 20 Sept 2026 ยท newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

diversified industrial cash flows provide funding for telecom, retail, and energy growth without one demand driver.

What to watch

Large project commitments could absorb cash before new businesses generate returns that justify investment.

+88.1%
Excl. dividends: +85.4%
0.3%Dividend yield (net)
โ€”Buyback yield
21.1x
Price as of: 2026-10-01
44/100
87/100

Flagship insight

Conglomerate Free Cash Flow Inflection Meets Complex Holding Company Reality

High consensus confirms the conclusion of heavy 5G capital expenditure is driving an inflection in consolidated free cash flow, cushioned by Jamnagar's complex refining margins. However, persistent holding-company stub discounts, regulatory windfall taxes, and Asian petrochemical overcapacity represent decisive structural risks.

A massive spending cycle has ended, transforming a major industrial builder into a high-powered cash generator. After pouring billions into nationwide 5G networks and modern retail stores, heavy construction spending is tapering off. This slowdown allows rising mobile phone bills and supermarket sales to turn into solid cash flow, while advanced oil refining provides dependable baseline profits.

  • Finished 5G network investments allow new telecom earnings to turn directly into cash rather than paying for construction.
  • Upcoming stock listings for subsidiaries bring transparency, but holding-company discounts may limit the immediate price benefit for parent shareholders.
  • Weak global chemical profits and possible government export taxes on fuels could slow down overall profit growth.

Advisor consensus

Overall, advisors show very high price-direction agreement and low disagreement. Read on to see where advisor views still differ.

The decisive debate centers on whether subsidiary public listings will eliminate or entrench the conglomerate holding discount. Constructive perspectives assume that independent market price discovery for digital and retail divisions will automatically force an upward re-rating of the parent stock toward intrinsic sum-of-the-parts value. Conversely, skeptical analyses emphasize that fresh-issue IPO structures trap proceeds inside operating subsidiaries, leaving parent common shareholders with diluted stakes and a discountable stub. This tension will be resolved by observing post-listing trading dynamics: whether the implied parent stub trades at an expanded multiple or suffers standard holding-company haircuts.

Risk and opportunity map

Longer-term opportunities

Synchronized pure-play demerger of consumer arms

Capital Allocation

36% probabilityStock price impact: +30.0%Earnings impact: Not quantified

Management executes tax-neutral corporate spin-offs of both telecom and retail entities by 2028. Establishing independent pure-play listings dismantles the conglomerate holding discount entirely, allowing digital assets to command software-utility multiples and retail to trade at premium consumer benchmarks. This restructuring unlocks substantial trapped shareholder equity across public bourses.

Commercial green hydrogen global export breakthrough

Innovation And Product

26% probabilityStock price impact: +24.0%Earnings impact: Not quantified

Jamnagar achieves levelized green hydrogen production costs below $1.50 per kilogram ahead of schedule, securing long-term export off-take pacts with European and Asian industrial consortiums. This transforms new energy from a capital-intensive project into a high-margin export engine, significantly elevating group terminal growth rates and valuation multiples.

Tail risks

Protracted maritime blockade severing crude feedstock

Political And Geopolitical

22% probabilityStock price impact: -28.0%Earnings impact: Not quantified

Escalating Middle Eastern military conflict completely halts crude tanker transit through the Strait of Hormuz for multiple months. Despite Jamnagar's feedstock agility, acute physical shortages force run-rate throttling and trigger severe demurrage and insurance penalties, eviscerating downstream operating cash flow and inflicting severe balance-sheet strain.

Aggressive regulatory antitrust intervention and price caps

Regulatory

19% probabilityStock price impact: -20.0%Earnings impact: Not quantified

Indian regulatory bodies impose statutory tariff caps on mobile data or mandate structural unbundling of integrated retail supply chains to protect competition. Halting telecom ARPU growth and capping grocery margins would destroy projected operating leverage, compressing enterprise multiples across consumer divisions.

The finalists

The Top 3

#3 โ†’ #1

The shortlist is over. These three stocks earned the strongest conviction in this edition. Count down to the research team's number-one pick.

Checking your access...

The winner

The Number-One Pick

The edition's highest-conviction selection, combining near-term opportunity with long-term confirmation.

Market context and selection approach

Markets remain selective, so this review emphasizes power demand, commodity exposure, capital spending, regulation, and cash generation. Current evidence can support a thesis while still leaving meaningful company, policy, liquidity, or macro risk.

The list favors the strongest supported investment cases in priority order and stops when enough qualifying opportunities are available; price movements alone do not determine whether a case remains credible.

References

Frozen links are separated into editorial-review evidence, 5โ€“6 global-context references, and 3โ€“4 governed Researcher citations per selected asset. Duplicate URLs appear once; the combined citation list is capped at 30.

A. Editorial-review sources

  1. 1.Lithium Americas Corp - frozen Batch 7 consensus research iPulse AI ยท SPECIALIST SECONDARY ยท 21 Sept 2026, 07:13 UTChttps://ipulseai.com/stocks/lithium-americas-lacReviewed for: Lithium Americas Corp (LAC.NYSE)
  2. 2.Power Grid Corporation of India Limited - frozen Batch 7 consensus research iPulse AI ยท SPECIALIST SECONDARY ยท 21 Sept 2026, 07:13 UTChttps://ipulseai.com/stocks/power-grid-of-india-powergridReviewed for: Power Grid Corporation of India Limited (POWERGRID.NSE)
  3. 3.CATL - frozen Batch 7 consensus research iPulse AI ยท SPECIALIST SECONDARY ยท 21 Sept 2026, 07:13 UTChttps://ipulseai.com/stocks/catl-3750Reviewed for: CATL (3750.HKEX)
  4. 4.Reliance Industries Limited - frozen Batch 7 consensus research iPulse AI ยท SPECIALIST SECONDARY ยท 21 Sept 2026, 07:13 UTChttps://ipulseai.com/stocks/reliance-industries-relianceReviewed for: Reliance Industries Limited (RELIANCE.NSE)
  5. 5.Fluence Energy Inc - frozen Batch 7 consensus research iPulse AI ยท SPECIALIST SECONDARY ยท 21 Sept 2026, 07:13 UTChttps://ipulseai.com/stocks/fluence-energy-flncReviewed for: Fluence Energy Inc (FLNC.NASDAQ)
  6. 6.Belgian state and ENGIE extend nuclear heads-of-terms target ENGIE ยท ISSUER RELEASE ยท 30 Sept 2026, 00:00 UTChttps://en.newsroom.engie.com/news/the-belgian-state-and-engie-group-have-agreed-to-extend-the-target-date-for-concluding-the-heads-of-terms-until-4-november-2026-9047f-314df.htmlReviewed for: Engie SA (ENGI.PAR)
  7. 7.CNOOC Ltd - frozen Batch 7 consensus research iPulse AI ยท SPECIALIST SECONDARY ยท 21 Sept 2026, 07:13 UTChttps://ipulseai.com/stocks/cnooc-0883-hong-kongReviewed for: CNOOC Ltd (0883.HKEX)
  8. 8.BYD interim results for six months ended June 2026 BYD Company ยท ISSUER FILING ยท 28 Aug 2026, 00:00 UTChttps://www.hkexnews.hk/listedco/listconews/sehk/2026/0828/2026082801633.pdfReviewed for: BYD Company Limited (1211.HKEX)
  9. 9.BP plc - frozen Batch 7 consensus research iPulse AI ยท SPECIALIST SECONDARY ยท 21 Sept 2026, 07:13 UTChttps://ipulseai.com/stocks/bpReviewed for: BP plc (BP.LSE)
  10. 10.Strategy and Outlook Presentation 2026 TotalEnergies ยท ISSUER RELEASE ยท 28 Sept 2026, 00:00 UTChttps://totalenergies.com/newsroom/presentation-strategie-et-perspectives-2026-501175/?lang=engReviewed for: TotalEnergies SE (TTE.PAR)

B. Global market context

These dated files capture broader market, macroeconomic, policy, and cross-asset context. Each frozen file is supplied as input to every advisor model during deep analysis; its citations never count toward an asset-specific minimum.

This original edition uses the frozen global-context evidence embedded in each linked deep analysis; no separate post-analysis market-context review was added.

C. Asset-specific deep-analysis sources

Captured by governed AI Researcher agents. Shared URLs are shown once and identify every selected asset they support.

Asset-specific Researcher citations remain available in each linked deep analysis above; this original edition did not add a second citation set.

Important information

Research scope and investor notice

Research scope

  • Newer dated external evidence is NOT_RETAINED for assets without a newly opened primary source; evidenceRefs identify retained earlier documents or exact frozen consensus research.
  • Current event searches are incomplete and cannot establish the absence of all developments; VALID denotes the strict retained-thesis state, not comprehensive current-news assurance.
  • Undated protocol documentation was checked as context without inventing publication dates; issuer targets and research scenarios remain forward-looking.

Investor notice

AI-assisted editorial analysis. Reviewed and approved by Russlan Ramdowar. Published by Future Edge Group FZE. This is general research, not personalized investment advice.

Forecasts, ratings, and return estimates are uncertain and may change as new evidence becomes available.